[00:00:00 - 00:05:57]
Host: Today's guest didn't find his business. His business found him. Kyle Holmes had been the general manager of Quail Ridge Golf Club outside Grand Rapids for years when the ownership group pulled him aside and asked whether he'd ever thought about owning a golf course. He had in his dreams, but he was in his 30s with five kids and nowhere near the money to buy 275 acres in the most affluent suburb of Grand Rapids.
That turned out not to matter. Kyle and Tim, the core superintendent, bought quail Ridge for $7.3 million with none of their own cash in the deal, an SBA504 loan for 40%, a conventional loan for 50% and a seller note from that ownership group for the final 10%. Listen for how the SBA loans 25 year amortization and is what let a business throwing off 5 to $700,000 of earnings carry a $7.3 million loan. Also listen for the tension at the center of this deal.
The land alone is worth $10 million or more, considerably more than the golf course business. But Kyle and Tim needed the package valued based on the business, not the dirt, which made the three week wait on the appraisal the most nervous stretch of the process. Here he is, Kyle Holmes, managing owner and general manager of Quail Ridge Golf Club Insurance may not be the first thing you think about in due diligence, but coverage gaps and unexpected costs can all expose your target and affect the success of your transition. In a webinar today, Thursday, none other than August Felker of Oberly Risk Strategies will walk us through what you need to understand about insurance before closing.
A two time searcher himself and a longtime supporter of Acquiring Minds, August is immersed in our ecosystem and has delivered insurance solutions for countless acquisition entrepreneurs. Among the topics you'll learn what insurance due diligence involves and why it matters the types of insurance you may run into during an acquisition the biggest lessons Oberle has learned from reviewing so many searcher deals, which coverages you need and which are just nice to have and new insurance products that acquisition entrepreneurs are buying more often, like personal guarantee insurance. The webinar is Protect the How to Diligence Insurance Pre close and it is today, Thursday, September 24, noon Eastern. Link to register is right at the top of this episode's show notes or on the Acquiring Minds homepage acquiringminds Co.
Then this coming Tuesday, we're hosting leading SBA loan broker Heather Anderson of Viso Business Capital. A deal may look affordable based on the broker's numbers, but the lender's math can tell a very different story. Heather will take one fictional deal from start to finish to show how banks actually size an SBA acquisition loan, including how to rebuild adjusted EBITDA from the business's tax return, which add backs lenders accept, question or reject why the EBITDA a bank will accept is often lower than the number in the SIM how lenders use cash flow and DSCR to determine the maximum SBA loan, how seller notes, working capital fees and equity fill the rest of the financing gap, and what the deal would need to earn for the buyer to get a 30% annual return on equity. The webinar is sizing an SBA loan to the cash flow and it is this coming Tuesday, September 29th, noon Eastern.
Link to register is right at the top of this episode's show notes or on the Acquiring Minds homepage. Acquiringminds Co. Welcome to Acquiring Minds, a podcast about buying businesses. My name is Will Smith.
Acquiring an existing business is an awesome opportunity for many entrepreneurs, and on this podcast I talk to the people who do it. Longtime Acquiring Mind sponsor Aspen HR is now part of Engage peo. Engage helps acquisition entrepreneurs, business buyers like you, take care of their new employees and build trust from day one. Whether it's an asset or stock purchase, Engage provides a turnkey solution for payroll and taxes, hr, admin and technology, employee benefits, retirement plans, workers comp, and more.
They're also always a phone call away so you can receive HR guidance from licensed employment attorneys promptly as those inevitable people issues come up. With Engage managing your people infrastructure, you as new owner of your business, can focus on building relationships, operating the business and driving growth. To learn more, contact Jenny thier directly at jthear j t h e a r@ngagepeo.com or click the link in the notes. Kyle Holmes, welcome to Acquiring Minds.
[00:05:57 - 00:05:58]
Guest A: Thanks for having me.
[00:05:58 - 00:06:20]
Host: Kyle, you bought Quail Ridge Golf Club, a championship public golf course outside Grand Rapids. There is real estate and considerable land here, but from your perspective, you were absolutely buying a business. We will unpack that, but let's start off with some background on you, please.
[00:06:20 - 00:06:53]
Guest A: Kyle yeah, I grew up in northern Michigan, small town called Gaylord. My father's a golf course superintendent, so being around golf was my life, you know, since as long as I can remember. And that kind of fed into playing junior golf, high school golf. Kind of dabbled, you know, on the kind of the amateur thing for just a little bit, but not long enough to waste money or anything like that and just dove right into a career in golf where you know, right out of college, I have been assisting other people in running golf courses until I was able to run on my own.
And I've been doing that ever since.
[00:06:54 - 00:07:00]
Host: When you say running golf courses, you're running Quail Ridge now, and that was how you became owner?
[00:07:00 - 00:07:00]
Guest A: Part owner.
[00:07:01 - 00:07:06]
Host: Had you done that at other golf courses? Give. Give us just quick bullet points of your resume.
[00:07:06 - 00:08:10]
Guest A: Yeah. So upon graduation, you know, I began the assistant golf professional track. I was at Kent Country Club in Grand Rapids, Michigan. And then from there I got the assistant golf professional job at Sleepy Hollow Country Club trip just north of New York City, which, it felt like it was the big break that I needed, you know, to be around a very high level golf club.
And I parlayed that into an assistant job at Northfield Golf Club, south of Minneapolis, Minnesota. And that led into my first leap from being an assistant to straight to gm. And I didn't even do the head pro route. I took both titles on at the same time and never looked back.
So I spent three years there, spent three years at Coil Ridge Golf Club, and then I left to go run Harbor Shores Resort in southwest Michigan. And, you know, I didn't particularly enjoy it as much as I thought I was going to. Got a lot of great experience and was able to host a Senior PGA Championship and then came back to Quail Ridge and ran that for five years upon buying the golf course and continuing to operate in the general manager role.
[00:08:11 - 00:08:28]
Host: Okay, great. So that last piece there tells us that this is actually the case of you being an employee buying out his employer. Right. You were, you were running Quail Ridge already as the GM for a number of years?
[00:08:28 - 00:08:28]
Guest A: Yes, I was.
[00:08:28 - 00:08:33]
Host: And then ownership sold it to you. And this is, this is the story we're here to tell, correct?
[00:08:33 - 00:08:36]
Guest A: Yep, yep. Me and the golf course superintendent as co owners.
[00:08:37 - 00:08:54]
Host: Exactly. So you and the superintendent are 50. 50 owners in the business. We're going to get to that as well.
Okay, so you're the GM of Quail Ridge in 2013. So how does the prospect of buying the place start?
[00:08:55 - 00:09:36]
Guest A: Yeah, it started with a conversation with the previous ownership about their desire to potentially sell. And they had already had conversations behind the scenes about who they wanted to sell to. You know, in a lot of circumstances, I think golf courses are just put out an open market, highest bidder, see what happens. But since the golf course superintendent had been there since 1998, I got there in 2015, they.
They felt that they wanted us to buy it if we were in a position to do that. And so that, that began the conversation that led to us purchasing it, you know, and that stretch from that conversation to closing. A lot of things happened, but that's how it began.
[00:09:36 - 00:09:40]
Host: What was that? Those first conversations, like they approached you?
[00:09:40 - 00:10:21]
Guest A: They did, yeah. Just off the cuff conversation. What my hopes and dreams were. And in the context of the conversation, I thought it was more prying on whether or not I was considering leaving and going to a different golf course in the future, if I was happy where I was.
And then the managing owner at the time asked me if I'd ever considered owning a golf course, which I had in my dreams, but I hadn't put together a group or explored those actual realities at that point. So that that kind of really began the conversation of this seems more like a question of, can you do this? Is this something you want to do? And then from there, how do you do it?
[00:10:22 - 00:10:27]
Host: You said you had thought about this in your dreams. So is this a dream come true?
[00:10:27 - 00:11:05]
Guest A: Yeah, absolutely. Yeah. To be able to. To own a golf course and know that everything that my staff and myself and Tim, our co owner, put into it, we control our own destiny rather than having to, you know, work really hard, which most people do for somebody else.
And that is, that is how a lot of people make their living. And I understand that. But it's definitely changes your perspective on how you operate when, you know, everything you put into it is if you, if you make too many crucial mistakes, you're the one that suffers, not somebody else.
[00:11:05 - 00:11:18]
Host: Great. The ownership, describe it. This is one person, a couple people, multiple people. A group, Private equity.
Who. Real estate developers. Who owns it?
[00:11:19 - 00:11:54]
Guest A: When the course was Originally built in 1998, there was a group of 23 guys who were all members at a private club in a different part of the state in southeast Michigan, Metro Detroit. Throughout the years, many of them had gotten out for various family reasons or different career choices. So by the time myself and Tim had purchased it, there was nine of them, but there was really three of them. You know, there was six minority orders and there was three majority owners who controlled whether or not they could sell, when to sell, what that would look like.
And those are the three that I dealt with the most often.
[00:11:55 - 00:12:23]
Host: And so this place was founded by 23 people or invested in by 23 people. Were these golf entrepreneurs or were they just golf aficionados who had day jobs, were wealthy, had disposable income and said, hey guys, it would be fun if we spun up our own golf course? I mean, yeah, 23 owners. And then now at the, toward the end, you said eight.
Did you say three? Three primary, five minorities, three?
[00:12:23 - 00:12:26]
Guest A: Yeah, at that point, yeah, I guess there was eight because one of them had passed.
[00:12:27 - 00:12:35]
Host: Okay, so. So just say more about kind of the, the, the vision here, what they built, how it was kind of a,
[00:12:35 - 00:13:28]
Guest A: kind of a brief timeline and also various conversations throughout the years. I knew some of These ownership was 1998 was in the middle of the golf boom. Right. Kind of the early years of the Tiger woods era where golf was becoming really popular.
There were not a lot of golf courses compared to the amount of people that were getting interested in it. There was also a big play on buying real estate, building developments around it. Saw that happen all over the country. And then talking to the group of owners that I knew, they all played golf, but none of them, it was their career.
They all owned their own businesses, had their own careers, and it was an opportunity to diversify their portfolio and get in at the early stages of what became probably a 10 year rush of golf course builds throughout the country, you know, until the market crash of 2008 and 2009.
[00:13:29 - 00:13:48]
Host: Okay. And they thought it would be profitable. I mean, I guess what I'm getting at is was this also, or more of kind of a vanity play for, for guys with some disposable income, or did they actually think this would be a good venture? I guess they did because they were, as you said, they were being opportunistic because the market was hot.
[00:13:48 - 00:14:01]
Guest A: Yeah, I would say definitely it was. It was a way to continue to grow their portfolios and their individual wells in a market that at the time and throughout the beginning stages looked like it was just going to continue to climb and climb and climb.
[00:14:02 - 00:14:10]
Host: And then did it pan out for them? Was it a good investment? Did the place thrive as a business? What was the outcome for them as investors?
[00:14:10 - 00:14:58]
Guest A: It did in the long run, definitely. There was some tough moments, for sure. There was some off seasons as a seasonal golf course in Michigan where we have to close because of snow, you don't have any money coming in, but you're still spending money out on payroll and utilities and other bills that happen year round. So there was some time in the mid 2000s where I think that was probably a little tight, tighter than they would have liked.
But like anything, if you continue to follow trends and you watch it and you stick with it and you make sure that you have the right people in place to run it. Once you get through that, who knows what's going to happen, you know, and once, once the recession. Once we came out of 2008 and 2009, golf started to kind of slowly climb. And then the big change for most golf courses was after Covid.
[00:14:59 - 00:15:01]
Host: And what happened after Covid?
[00:15:01 - 00:15:23]
Guest A: After Covid or during COVID people were isolated, they were indoors. You know, they couldn't, they couldn't go to their local rec center to play pickup basketball with their friends or things like that. But the one sport that you could do is play golf. You were outside, you could be alone, you could be with a couple family members, but you were, you were outside.
And it has not stopped since then.
[00:15:24 - 00:15:26]
Host: So it boomed because of COVID and hasn't stopped.
[00:15:26 - 00:16:06]
Guest A: Absolutely. Yeah. And I think, you know, looking at, on a national scale, there's a lot of markets that are kind of returning to the mean of maybe 20, 21, 20, 22, but there's certain markets that are continuing to boom. And that is where golf is part of people's daily lives.
It's part of, you know, what they, what they believe in, how they operate, know how they want to spend their free time. And so you have Florida, you have Arizona, you have California, you have Michigan. You know, there are certain areas where golf has always been in the fabric of who the people are, and I just happen to have one in one of those states.
[00:16:07 - 00:16:14]
Host: So Michigan is a big golf state. Golfers will probably know that. It was news to me and somewhat counterintuitive.
[00:16:15 - 00:16:32]
Guest A: Yeah, yeah. I don't have the exact figures in front of me, but you know, golf courses, per capita of people, it's Florida, California, Michigan, then Arizona. And the only outlier is the fact that Michigan gets winter and the rest of these places do not.
[00:16:32 - 00:16:41]
Host: Right, right. Give us a picture of Quail Ridge. What? You know, the size of the land and the buildings and all of it.
What are we talking about here?
[00:16:41 - 00:17:11]
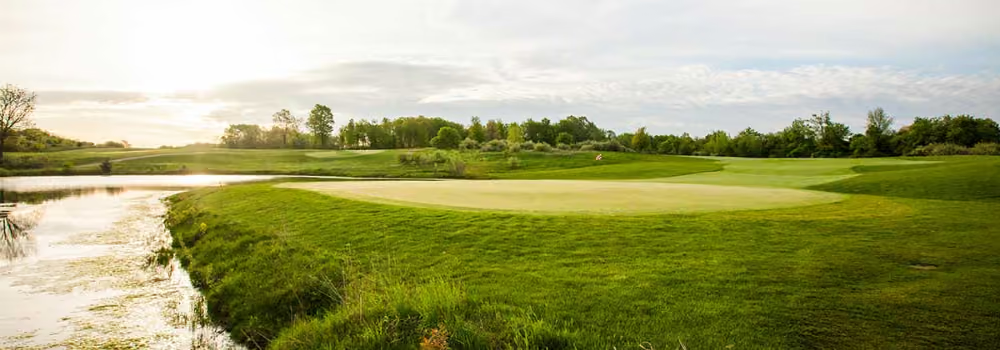
Guest A: So we have two hundred and seventy five acres. We have a main clubhouse with a restaurant, pro shop, offices, cart storage. Underneath, we have an event center which is its own separate building. We have a maintenance building where we house all of our equipment to take care of the golf course.
And then we have a pump house on the golf course, you know, for irrigation and things like that. And we're in the middle of constructing a year round indoor outdoor simulator system which will be open in the next two to three months.
[00:17:12 - 00:17:15]
Host: And the 275 acres of land, all of that is for the golf course
[00:17:17 - 00:17:27]
Guest A: in woods and wetlands, but all of it is within the, within the construct of what we own. Our golf course takes up probably about 155 to 160 acres of that actual land.
[00:17:28 - 00:17:31]
Host: And is that a typically typical sized golf course?
[00:17:31 - 00:17:49]
Guest A: No, not at all. No. I would say typical golf courses, especially in the, you know, the 50 to 100 year old golf courses that were, you know, built within the constraints of, you know, being around a metropolitan area or things like that. 150 to 160 acres is more than enough to have a golf course on with 18 holes.
[00:17:50 - 00:17:56]
Host: Okay, and you said that in fact is what yours is as well, then you've got the excess of the excess.
[00:17:56 - 00:17:57]
Guest A: Yeah, yeah, yep.
[00:17:57 - 00:18:00]
Host: Yeah. So this is a big piece of land.
[00:18:01 - 00:18:03]
Guest A: Yes, it is. It is very. Yes.
[00:18:03 - 00:18:30]
Host: Okay. Okay. Big piece of land and also big operation. I mean, you've got, I mean, you've got a restaurant which is its own little business.
You've got the shop which is its own little business. And then of course, you sell access to the links. So how does that work? What are the, are these many businesses under an umbrella?
Are they all give us kind of a breakdown of the, of the operations here and the business kind of how things are organized.
[00:18:30 - 00:19:06]
Guest A: Yeah, so it all operates as one entity, as one business. Golf accounts for about 70% of our total revenue for the year. Another 10% is our driving range. Another 6 to 7% is our just daily restaurant.
You know, people coming in, grabbing hot dog or a sandwich or something quick at the turn. And then the remainder of that number is through our event center. Weddings, graduation parties, memorials, anything that is community based where they need a bigger space than what our clubhouse offers.
[00:19:06 - 00:19:11]
Host: And what does it mean to be a public golf course as opposed to private or membership?
[00:19:11 - 00:20:02]
Guest A: Yeah. So the difference between public and private is anybody at any time can go on our website, book a tee time, show up, pay the fee, and play our golf course. At a private golf course, you have to join. Some golf courses have initiation fees and then they have monthly or yearly dues.
Other people can come on and play those private golf courses, but they have to be with or invited from a member of that course. And so typically private golf courses have about three to 450 private golfing members, you know, not including kids, spouses, Whereas we have 45,000 golfers roughly a year. And you could come up and play, somebody could come from around the corner, you could be, you know, vacationing from the south in the, in the summer to get away from the heat. Anybody can play a golf course at any time.
[00:20:03 - 00:20:11]
Host: But to be clear, when you say public, that doesn't mean any sort of local government ownership or involvement. It just Means non member.
[00:20:12 - 00:20:23]
Guest A: Yeah. So the distinguishing factor there is public versus municipality owned. Municipality would be owned by a local government or a township or a community or a county.
[00:20:25 - 00:22:13]
Host: Running payroll, paying your bills, closing your books and producing financials. These are critical tasks every business owner must do or oversee. But spending time on them distracts you from the leadership in growth work you want to do. So let system 6 do it for you.
Owned and led by a former Searcher, Chris Williams, System 6 is a leading outsourced finance team for hundreds of SMBs, including over 50 searcher acquired businesses. Chris, Tim and the System 6 team understand firsthand the challenges, the opportunities of jumping into a business as its new owner. So whether you own your business already or have one under LOI, talk to System 6 about how they can give you time back and improve your financial operations. Mention acquiring minds and they'll provide a free review of your books and financial ops, a $500 value.
Check out system6.com link in the show notes or email helloystems6. The ownership group approaches you asking if you'd ever want to buy or, or own your own golf course. Are you already independently wealthy? I mean, I would just think that I wouldn't target somebody as the buyer of this if I'm the owner who I don't already think is worth millions of dollars.
This, I mean, I, I can't be more specific than that, but it certainly seems like it would be in the millions of dollars to acquire something like this, which in fact we will find out. It was. So. So was it as odd to you that they asked you as it sounded to me?
[00:22:13 - 00:22:38]
Guest A: It was absolutely. You know, I'm still in my 30s, I have five children and so independently wealthy to the level of just outright buying a golf course with my own money was not in the realm, you know, and they knew that. But nonetheless, it didn't make that initial, you know, ask less off guard than, you know, you took it as well.
[00:22:38 - 00:22:45]
Host: Yeah. And so what do you think they saw in you or why do you think they approached you at all?
[00:22:46 - 00:23:29]
Guest A: I think over the eight plus years that I'd worked for them, they knew that a lot of things that we had done or tried, you know, to add to our golf course, you know, whether it be adding GPS to our golf cart experience or putting top tracer on a range, you know, which we were the first ones to do in Michigan, I think they knew that even if I didn't know how to do it, I would, I would at the very least find the information on how it could be plausible. And if that came back and it still wasn't plausible, then I'm certain that they would have moved on to, you know, a different group of people. But I think at their core, they really wanted to sell to Tim and I, and they knew that I would find the answers to make it happen if it was possible.
[00:23:30 - 00:23:33]
Host: And why did they, at their core, want to sell to you and Tim?
[00:23:34 - 00:24:17]
Guest A: Because we had taken them to new heights from where they were in the early 2000s and post recession. And I want to say that the golf course was struggling, but it wasn't turning a profit like it could have been for various reasons, you know, market economics, you know, poor people that were managing it at the time, whatever the case may be. And then when I got there, you know, that started to turn around, and the course conditions were always good. So Tim always had that history of, like, he was really, really.
It still is really, really good at his job. And then I came in and kind of formed, like, what they were missing.
[00:24:17 - 00:24:52]
Host: And was there some emotional component, do you think, to wanting to sell to you guys, as opposed to putting it on the market and selling it to the highest bidder? I mean, is there. What do you think? I guess what I'm kind of driving at, is there some sort of community orientation to them that they want this to stay how it is?
A lot of sellers have a sentimental view of the future of their business, of the succession of their business. Some sellers don't. They'll just sell to the highest bidder. What do you think their.
Their. Their view or their. Their feeling was on. On that front?
[00:24:52 - 00:25:56]
Guest A: I think there was a lot of emotion behind it, knowing that they were not a part of the West Michigan community. None of them lived there. None of them had ever lived there. And Tim and I both live in Ada, which is where our golf course is located.
You know, so our kids go to school here. You know, we're a part of the community. And then another factor, and I don't know this for sure, but it seems to kind of to stick. When I connect the dots, is there is a local group that over the last probably eight to ten years, has bought up eight or nine golf courses around us, you know, within, you know, 40 miles.
And they. I know for sure that they had approached the previous ownership about wanting to buy Quail Ridge as well. And so I think there was this emotional tie of we don't want to become a part of a group that everyone, you know, takes a bunch of golf courses and lumps it into one Entity. Quail Ridge has always been its own unique place, and I think that at their core, they really wanted to keep it that way.
[00:25:59 - 00:26:41]
Host: Well, what I'm also hearing here, Kyle, is that. Is that that's a big factor probably, but also, you are what we hear a lot about in small business land is kind of a rock star. Gm, You're. It's so hard to find great management of a business that will.
That is, you know, can not only keep the trains running and just keep things organized hard enough to find somebody to do that competently, but will actually introduce growth into the business and introduce vision. You seem like you're something of a visionary. You. You want to keep up with the market.
You push. You push the business.
[00:26:41 - 00:26:41]
Guest A: You.
[00:26:41 - 00:27:58]
Host: You push Quail Ridge, you probably push the ownership to do X and Y and Z. And I think that's a. And you had demonstrate they knew you. You were a known entity, so.
So they'd seen you operate for years, and it sounds like you were instrumental in really leveling up Quail Ridge when it was not doing so well. And a lot of that is to your and probably Tim's credit. So what we hear about. So.
So, you know, you're the unicorn that small business owners want to find there. And then also, when it comes to selling their business or a succession plan, you'll often hear a lot of owners say, you know, there just isn't somebody in my organization I think that I could sell to that could really handle, level up into really thinking like an owner and behaving like an owner or even figuring out how to get the transaction done. It's a big lift to get a transaction done, and then becoming owner is its own separate, longer, heavier chapter. And so.
But in you, they saw, you know, as a unicorn. In you, they saw somebody who could handle who they thought could handle it all if. If your appetite was. Was up for it, which it sounds like it was.
Do you think that's an accurate. I'm putting words in your mouth because you're not going to pump your own tires, so I'm pumping them for you. But do you think that was an accurate take?
[00:27:59 - 00:30:11]
Guest A: I would agree with that because throughout the years that I worked for them, I was very, very fortunate. I don't think a lot of people that run small businesses for other people get this ability that I was given is our ownership had so many other things going on in their own businesses that were much bigger and more profitable than a single golf course in West Michigan that, you know, once they got comfortable with understanding How I operate and my attention to detail, how I worked alongside Tim, our communication, how our staff ran. You know, they. They really kind of handed the reins over where for probably six or seven years, I felt like I was operating as an owner because they.
They weren't. They were looking at the financials once a month and would have conversations and questions and. And they expected me to be able to answer them, and I knew they expected that of me. So if I came to them in the off season with a proposal and said, hey, I think that we should do this and it's going to cost X amount of money, it wasn't just on a whim in hope that they say yes.
I mean, I was going to get drilled with questions on what are we going to charge? How much is it going to make us? What are the shortfalls, what are we missing here? You know, and so I got into that mindset a long time ago on you can't innovate, you can't have vision, you can't do these things when you don't own something unless you're prepared, like you're the person who owns it, you know.
And now I get to have that conversation with Tim, who has come back to me and said, have you thought about xyz? Maybe this is a great idea, but what about two years from now? And that's where communication between him and I, like, communication between him, I. And the previous ownership has been so crucial, because otherwise you're kind of just guessing and hoping you're going to believe in somebody's idea, that maybe you concept it up in the shower one morning, you know, long drive, you know, and that's.
It's a great. It's a great starting point, but it's not a way to pitch something to somebody.
[00:30:13 - 00:30:16]
Host: Tim is. Is the superintendent. What is that? What does that mean exactly?
[00:30:16 - 00:30:48]
Guest A: So he's in charge of making the golf course look the way that golf courses should look if somebody knows what they're doing, you know. So he oversees the staff that, you know, mows the greens, fairways, tees, rough, takes care of, you know, the grounds, around the building, our front entrance, all that. He leads that staff. And he also, you know, is.
Is the expert in the field when it comes to what kind of product do you put on your tees, greens and fairways, given the weather, how often do you water anything that makes our golf course look better? It starts and ends with him.
[00:30:49 - 00:31:06]
Host: Yeah, and so it's. To call it landscaping would probably be to really understate it, because there's all sorts of other considerations on top of it looking pretty to make it a high, you know, high end experience for the, for the end user, the golfer.
[00:31:06 - 00:31:51]
Guest A: Yeah. I mean, I don't know a ton about the landscaping industry, but I would think that for the most part it's mowing somebody's lawn when it gets long. Where for Tim, like, he knows, you know, we mow our greens seven days a week, we mow our fairways three days a week, our tees three days a week. So that stuff's already kind of baked in just like you would as a landscaper.
But on his end, it's, what's the weather? What has it been the last five to ten days? What's it look like the next two weeks? Is it going to get hot?
Does he have to put wetting agent on the green so we can retain water when we water it so the grass doesn't burn out? You know, when you have a lot of moisture and you have high humidity, you might get dollar spot and other diseases that are going to make your turf look poor core. You know, he's seeing that stuff before it happens and putting product on it to combat it.
[00:31:53 - 00:31:56]
Host: And so you said your dad was, did what Tim does.
[00:31:56 - 00:32:28]
Guest A: Yeah, and my brother does it currently. And so I think that that's what has allowed our communication to always be so good, is I grew up on, in his world. I just chose the business world of golf, you know, so most, most people in my position, they know what golf course superintendents do, but they, they don't actually see it or hear about it or live in a home where it's, you know, the ebbs and flows of a season of weather is important. And I, that, that was my childhood.
It's been my life.
[00:32:28 - 00:32:38]
Host: Yeah. Okay, Kyle, Fascinating. Tell us about the business of Quail Ridge. Revenue, earnings, how basically how to think about this from the perspective of a business buyer.
[00:32:40 - 00:32:46]
Guest A: Yeah. Are you asking me as somebody wanting to buy a different golf course or how our business operates?
[00:32:47 - 00:32:51]
Host: How does you, how does Quail Ridge. What is the revenue in the, in the earnings of Quail Ridge?
[00:32:51 - 00:33:28]
Guest A: So 2025, which was the first year that we owned it, we did $3.3 million. We spent 2.1 million in expenses. So our, our NOI was 1.2 million. And then below that, you know, as a, as a new business owner, you have a bunch of depreciation at your disposal.
You have interest, which is way more than your principal payments. And then we throw our cart lease in there as well, just because it's a common reoccurring thing that we have. And so last year we were just shy of $700,000 in bottom line revenue in year one.
[00:33:28 - 00:33:35]
Host: Was that 700 of cash flow or 700 of EBITDA? 700 of cash flow that actually came out.
[00:33:35 - 00:33:39]
Guest A: Yeah. Of the business like that. That was available to roll in?
[00:33:39 - 00:33:52]
Host: That was available. Yeah, yeah, yeah, yeah. And okay, great. So that was last year.
And what about what were the numbers that, that were before you bought it so that you were looking at to assess what you should buy the business for?
[00:33:53 - 00:34:26]
Guest A: Yeah. So the last two to three years, which were our two to three best years, you know, they were in between that half million and $700,000 of bottom line take out cash at the end of the year if they wanted it. The biggest difference was their, their bank loan and whatnot had been paid significantly down over the last 20 plus years of them owning it. And so, you know, for us to get to the number that we got to the first year we owned it, we knew that we were going to, at, at a very least, we're going to lose about 350 to $400,000 of that in just additional interest
[00:34:30 - 00:34:33]
Host: because of the loan that you used to buy it. You were going to have this big. Yeah, sure.
[00:34:33 - 00:34:58]
Guest A: So there was a little bit of pressure and stress of knowing, hey, we can continue to operate how we have, which is a highly profitable business in the golf world, but how do we get it back to the level that they were at the year they sold? And we were fortunate enough to have a great weather year, we made a couple changes, we added some new features, things like that, and it worked.
[00:35:00 - 00:35:17]
Host: Right. So you're, the numbers that you're looking at before you buy it are 5 to 700,000 of earnings a year. Yep. And, but, and then under your ownership, you're expecting that that could half, because half of it's now going to go to interest under your ownership.
[00:35:17 - 00:35:17]
Guest A: Yep.
[00:35:17 - 00:35:27]
Host: And then happily, you've grown it so much or last year in 2025, you grew it so much that, that in fact, even after your debt payments, you were at 700,000.
[00:35:27 - 00:35:31]
Guest A: We're right in line with, with the best that they had ever been at. Yeah.
[00:35:32 - 00:35:48]
Host: Fantastic. Congratulations. Okay, so 5 to $700,000 of earnings a year, but it's got all this real estate. It's got 275 acres.
How do you value this business? How do you, what offer do you make these owners?
[00:35:49 - 00:36:36]
Guest A: So that was the, that was the me figuring it out, you know, online research of how golf Courses get valued whether or not there's homes involved, because some will sell as an entire development with neighborhoods or land where neighborhoods are going to go in. We didn't have any homes on the golf course. There are a couple houses have views of our golf course, but they're, you know, not part of our land, but the land feature. And in Ada, Michigan, Ada is the most affluent suburb of Grand Rapids.
I think it's second or third only to Birmingham, Michigan, and then somewhere up near Traverse City, you know, where it's beautiful for four or five months a year tops. And so the land itself was more valuable than the golf course could be, but we wanted to buy it as a golf course.
[00:36:37 - 00:36:43]
Host: So the land was way more valuable than the golf course business. But you wanted to buy it as a golf course business. Okay.
[00:36:43 - 00:37:16]
Guest A: For many reasons. I mean, for the community aspect, for the fact that, you know, that's Tim's job. That's my job, you know, so if we were going to buy it to, to turn around and sell it as just a block of land for some big home developer to come in and turn it into, you know, multiple neighborhoods, it may have been good for us, but it wouldn't have been good for any of our employees. You know, in peak season, we have over 100.
And then it would have left Tim and I, who are both still working age, to find a job, and I. Neither one of us want to leave.
[00:37:17 - 00:37:29]
Host: Did you value the business, the golf course business, at, you know, at what we would typically see in small business land of 3 to 4 times earnings. So in your case, you know, 1.5 to 2.5 million.
[00:37:30 - 00:38:17]
Guest A: Yeah. So golf courses typically trade depending on, you know, with the market where you're at and whatnot. Anywhere from 4 to 9 x EBITDA. Oh, it's kind of.
And it's quite the spread because it depends on what they have, how old their buildings are, you know, what deferred maintenance is out there. There's. There's a lot of factors in that. And so knowing that I was going to, Tim and I were going to have to make an offer to kick start the process.
We didn't want to come in grossly low because they, you know, they knew that we knew enough about the business, but we didn't want to overvalue it and buy it too high, you know, and so our initial offer was lower than what we ended up settling at. But it, there was a lot of research and time that went into that. Before that process, before that offer actually
[00:38:17 - 00:38:32]
Host: went out, when you Say that golf courses typically trade for 4 to 9x, a very, a wide range. Do they typically. Does that include the land that they're on because they're inextricably tied to one another?
[00:38:32 - 00:39:17]
Guest A: Yeah, most often. But you have to also assume that our golf course doesn't operate like most golf courses do as far as profitability. You know, you can go out and find a public golf course that might do half the rounds we do with an EBITDA of, you know, 80,000 or close to break even. You know, you can't buy that much land with that much equipment that comes with it, with a, with a liquor license, chairs, tables, you know, everything that comes with actually buying a golf course, you can't buy it for $0 because it would be.
Nobody would ever sell it for $0, you know, so it's such a hard business to place a value on because it solely depends on what the golf course is, what it does and what it has.
[00:39:18 - 00:39:45]
Host: Great. Yeah. I mean, I don't even know how you'd approach this. And I would just imagine in your case that the value of the land would so outweigh the value of the structures, the real estate on the land or the operating business itself that I wouldn't even know how to approach it.
Maybe I'm overestimating the value of the land. Anyway, why don't you tell us? So how, so how did you come to a formulation here of the, of your offer?
[00:39:45 - 00:41:01]
Guest A: Yeah, so I looked at a couple public golf comp sales, which there's not, There was not very many of comparison. Wasn't, wasn't a great factor there. I looked at the, you know, the 4-9x EBITDA and what that is. And that would have pushed us into a realm if we went on the high side, that would have been far beyond with our, with our new loan that we would have to take to make that profitable for a very long time.
But I also looked at the, the land and what it could go for on its own. And so we settled on. Our initial offer was 6.5 million. Not what we ended up closing at, but that was our initial.
And that felt like a number that was low enough that we could make money off of it, but not to, you know, throw mud in the face of the people we wanted to buy it from. It would also allow, knowing the previous ownership group and how, you know, how much they know about business to come back with a counter. And so we could continue the negotiations because the last thing either one of us wanted was to put an offer out there and then say, this isn't going to work, we're moving on. Because then the same thing would happen that was sold to somebody else and we would not have had jobs.
It was a very, very delicate balance.
[00:41:01 - 00:41:09]
Host: And when you researched what you thought the land might be worth, just apart from the business, what did you find?
[00:41:09 - 00:41:35]
Guest A: Well, not all 275 acres you can build on, you know, like half. We have a hole where we own half of a lake. We have several wetlands, and there's certain areas where you just cannot build, you know. So 275 acres is not 275 acres of buildable land.
Looking around at like what land comps were going for in Ada, I figured that the land in the, in its current state was worth at least 10 million.
[00:41:35 - 00:42:43]
Host: Wow. Okay, so obviously here, you know, your offer is under what the market value of this asset is in just the land alone. But going back to their motivation, there's a sense that they just really want you to be owners of it. They, they probably don't want this to be for Quail Ridge to be shut down and sold to a developer either, but they're not gonna just, they still need to see some sort of reasonable sale price.
So it's, it's probably delicate for them. In their own minds. They probably have a threshold number where it's like, we're not going to try to optimize the sale value here because the total totally optimized value would be frankly shutting the place down and selling the land. Yeah, we don't want to do that.
So how do we, you know, get to a number we're comfortable with that is not the actual market rate of what this asset could go for? Tricky. Okay, so six and a half million and what. And so is what do they counter with or where does it land?
[00:42:44 - 00:43:12]
Guest A: So they countered in my head, before we made that offer, knowing that there was going to be a counter, I thought worst case scenario, they'd counter 8. 7.5 was kind of as high as Tim and I would accept without wanting to counter offer ourselves back. And they get back into that tricky, like how long are we going to do this for? And so they came back at 7.3 and we agreed.
So it's just we made one offer and they made one and we accepted.
[00:43:15 - 00:45:19]
Host: Okay, 7.3, you know. Enzo Technologies as one of the leading IT managed service providers serving the search community, led by Nick akers, an Acquiring Minds guest who bought the 35 year old business. The team at Enzo regularly works with searchers and their acquisitions. And one feature of acquired businesses that Enzo is seeing over and over is the need to implement cybersecurity promptly during the transition.
So many acquired small businesses either have glaring vulnerabilities, lack security best practices or both. That step one to de risk the deal you just closed should be addressing these issues. INSO is your full service IT MSP form for post close stability. They assess your target, surface the biggest risks in plain English and give you a day one through 30 plan to cut exposure, prevent downtime and even find cost takeouts like bloated telecom bills.
Check out enzotechnologies.com I N Z O or email Nick directly at nick@enzo technologies.com so Kyle, just again on this, on this kind of lopsidedness of the transaction where you've got a business that is generating 5 to 700,000 and then you've got, but it's sitting on this land whose market value is, is frankly way higher than a business doing $700,000 a year of earnings. And it was going to get appraised. You would, you would get it appraised, the land? I, I, I'm just, I'm just kind of confused as to if a lender or somebody along the way would say you can't do this transaction the way you want to do it because the land is too valuable.
Did that come up, how did that work?
[00:45:20 - 00:46:57]
Guest A: It did. It, it came up in discussions with our, our private bank commercial loan officer that we were going to have to go through an and I've bought and sold homes before. And so to me it was just you hire whoever's local and they run market comps and you get a price based on square footage and how old the home is and things like that. Golf courses are much different because there's not nearly as many of them and none of them are the same by any means.
Land size, operational value, things like that. And so we ended up hiring a company out of St. Louis who specializes in appraising golf courses throughout the country. And so a gentleman flew up.
We met with the owners that were selling to us, him, Tim and I and our entire focus throughout the conversation was trying to pump up the value of the business as far as looking at all of our numbers and trying not to talk about the land as much as we could, you know, mentioning how many wetlands we had and how, you know, our, some of our soil sits on clay which could be tough to build on to get that appraisal expert to appraise at the number that we had agreed on. But as a professional in, in his industry, we didn't know how it was going to go. You know, you had the conversation. He tours the golf course, he looks at all the financials, takes pictures of all the buildings, and then we wait.
We waited for about six months.
[00:46:57 - 00:47:02]
Host: And what would have happened if he had appraised way higher than the 7.3 million you had agreed up to?
[00:47:02 - 00:47:50]
Guest A: We would have had to either up our offer, which if it would have been too far beyond where we wanted to go, we weren't prepared to do, or the owners were going to have to have. Have more skin in the game, or say, hey, we're going to. We're going to give you guys 30% of this in the seller's note, and we're going to spread it out over whatever terms that we decided it would have been, worst case scenario. Because at that point, we were probably three months into the process of going through, you know, hiring lawyers and doing all the things that you have to do when you buy a business.
And so it was about three to three and a half weeks from the time the appraisal. The appraisal expert flew out of grand rapids back into St. Louis. And when we actually got the report,
[00:47:52 - 00:48:19]
Host: and before you tell us the punchline, what happened if it had come back at, say, 12 million? Right. Way more than you were prepared to pay? Why you're making it sound like that would have then required the owners to sell you at that price, sell it to you at the appraised price.
Why couldn't they just say, okay, that's great. It appraises at 12. We still want to sell it to these guys, to Tim and Kyle for 7.3.
[00:48:20 - 00:48:33]
Guest A: Well, at that point, it would have taken us out of the SBA 504, because we would have fallen. We would have fallen outside their parameters of how much revenue you can make in a year. So it couldn't go north of 10 knowing that. And then.
[00:48:33 - 00:48:51]
Host: But couldn't they just say, we want to sell it to these guys? We don't care what the appraisal says. We want to sell it. We, the owners, want to sell it to Kyle for 7.3.
So I guess I'm. I'm wondering. I'm just. I'm getting hung up on why the results of the appraisal matters so much.
[00:48:52 - 00:48:56]
Guest A: They could have, like, absolutely, okay, but we didn't know.
[00:48:56 - 00:49:13]
Host: I guess, I guess if the. The appraisal came back high 12 million, then your owners, the sellers, would have just been really uncomfortable selling to you at 7.3. They would have said to themselves, we can't. We.
We can't justify selling this business for so little, I guess, is what we're.
[00:49:13 - 00:49:56]
Guest A: If the roles were reversed, it. It would have changed my thought process. As far as we've identified the people we want to sell to. We've had conversations, we've talked through it.
This feels comfortable. Wow. We didn't know we were sitting on a golf course that was actually worth X when we just accepted an offer at Y, you know, which is about. Could have been $5 million difference, could have been 3 million.
They may have done exactly how you explained it. I don't know that. I just think as human beings, when you have an asset and somebody tells you that it's worth way more than you were willing to part with, it probably would have changed the dynamics of how the rest of the process would have gone.
[00:49:56 - 00:50:42]
Host: Yeah. Yeah. Okay. Because like, in a, In a residential real estate situation, if you make an offer on a house and then what you worry about is that the house appraises for less than you're paying it for, and then the lender says, well, I'm not gonna.
I'm not gonna give you a loan for something that is actually worth less than the loan value we agree to. And so you. Somebody needs. Either, you know, seller needs to come down in price, or you need to bring extra cash to the transaction in a real estate context.
But if it over appraises, if it appraises it higher than the transaction was agreed to, I think I have this right. It shouldn't be. It's not a problem. It's just.
It's only a problem if it goes. If it comes in lower, not higher.
[00:50:42 - 00:50:54]
Guest A: So interesting that you say that, because I had never thought about it appraising for less than what we offered. It was never a concern about that. I always thought I was going to appraise for more.
[00:50:55 - 00:51:18]
Host: Exactly. And, and. And that's why I'm. I'm wondering why it mattered so much, because it seems like it would comfortably appraise for more, if anything, and why that would be a bad thing.
But it, but you were worried that it would appraise for more, actually. And it sounds like that's because of how it could have affected the psychology of the sellers. And if, if it appraised for way more than you guys had agreed to.
[00:51:18 - 00:51:19]
Guest A: Sure.
[00:51:19 - 00:51:22]
Host: Yeah. Okay. Okay. So what.
What did it come back at?
[00:51:22 - 00:52:28]
Guest A: It appraised at 7.3 million, which is on the nose. Right. And I, I have to imagine that as somebody who appraises probably 50 to 100 golf courses as an individual. This gentleman, for a company that does even more than that, he's probably had, you know, hundreds of conversations like the one he had with us at Quail Ridge the day that we met him, but I didn't know that.
I didn't know. I didn't know if, you know, they tried to appraise it right on the number. I mean, he was pretty guarded about how their processes work. He was a professional.
And so looking back at it, it seems that that's probably how it goes more often than not. Yeah, I just didn't. I didn't have that information. I had never talked to anyone who had gone through a golf course.
Golf course purchase before in whether or not they had the same kind of three week, like, I don't know how this is going to go type of process. And so I was just trying to figure things out in real time based on the information I was taking in during that day. Sure, sure.
[00:52:29 - 00:52:40]
Host: Okay. But your point in saying all that, too, is that you think that appraisers steer things in the direct. Because he knew. He knew the 7.3 number going in.
[00:52:40 - 00:52:42]
Guest A: He did know that. Okay. Yes.
[00:52:42 - 00:53:35]
Host: Now, but how, Kyle, are you going to finance a $7.3 million loan with just $700,000 of earnings? Because the loan service, I mean, this is why the, you know, the debt service coverage ratio, basically. So, you know, you get the size of your loan, the size of the earnings of the business. The ratio of that to your loan payment needs to be something reasonable.
But if you're taking. You're going to take this big loan for $7.3 million, even though we rec. We recognize that that's a good deal for what this is. How are you gonna.
How are you gonna pay for the loan payments if you just got half a million dollars, $700,000 coming out of actual earnings to use toward that debt payment.
[00:53:35 - 00:55:18]
Guest A: Yeah. So while we were going through this, valuing the golf course offer, counter offer, I was also trying to figure out if an accepted offer happens, what are the next steps? And in my research, I found this program through the SBA called a 504 loan. And so there's.
There's parameters to can't make more than. I think it's $10 million, but it has to make at least two. There has to be real estate involved, there has to be equipment involved. And so we fit all those parameters, and once you read into that, banks will latch on to anything that the SBA will back.
So you can pass the responsibility on if it was just the worst investment possible. And so when that became a reality, it allowed us to start to seek out a private bank to have that conversation saying, this is how we want to finance it. We're not asking you for 80 or 85% of the total purchase price. We're asking you for 50% of it.
The SBA will provide 40% of it. We get the amortization of 25 years from the federal government, the backing of the federal government. We only need 10% of our own. And it really, really changed the structure of the conversation.
Instead of calling and not even getting meetings, we started getting meetings. Rather than just two guys who don't understand, you know, how to buy something asking the bank for their backing. It would have never worked.
[00:55:18 - 00:55:25]
Host: And so sorry, the, the breakthrough there was that you could the five the existence of the 504 program.
[00:55:25 - 00:55:25]
Guest A: Yes.
[00:55:27 - 00:55:38]
Host: And so you pitched banks by saying some piece of the loan would be 504 and some piece would be what would the recipe. And like, why didn't you just go all 504?
[00:55:38 - 00:55:53]
Guest A: Because they, they won't go. They'll only go up to a certain level, depending on where your purchase price is. So, so I don't have the documents in front of me, but you know, the way that I viewed it, I was looking at a 50, 40, 10 split. The government was going to take 40%
[00:55:53 - 00:56:01]
Host: and fund it, meaning the SBA 40% was going to be the SBA 504 loan. Okay, that's 40%.
[00:56:01 - 00:56:10]
Guest A: We needed 10% of our own equity, which left us with 50%. So half of the purchase price is what we needed to ask banks for.
[00:56:10 - 00:56:14]
Host: Gotcha. You needed to. So in the form of a conventional loan.
[00:56:15 - 00:56:15]
Guest A: Yes.
[00:56:16 - 00:56:29]
Host: Okay. But when you talk about the government, the, the 40% SBA 504, that's still fundamentally who you're going to be dealing with is a lender. A lender who's giving you issuing an SBA504 loan. Right?
[00:56:29 - 00:57:08]
Guest A: Yeah, but the, the, the private institution has first rights on in the seven. The SBA has second. And the private bank also gets the benefits of the 25 year payment structure of an SBA 504 loan rather than a conventional loan, which can run anywhere from five to 10 years if you're lucky. I felt like it was going to be 5 to 7 would be best case scenario.
And so now they get 25 years to spread our payments out, which lowers our monthly payment, which made our profitability on a yearly basis much more enticing.
[00:57:11 - 00:57:37]
Host: So you find. So you're going to do. 40% of the purchase price of this 7.3 million is going to be SBA504 debt, which is going to be amortized over 25 years. And then another 50% of the 7.3 million is going to be a conventional loan and whose amort amortization schedule is tied to the SBA 504 loan.
So 25 years.
[00:57:37 - 00:57:38]
Guest A: 25 years.
[00:57:38 - 00:57:42]
Host: So 90% is going to be tied. Is going to be 25 years.
[00:57:42 - 00:57:42]
Guest A: Yep.
[00:57:42 - 00:57:55]
Host: And so that brings down the debt payment in line to something that 5 to $700,000 of annual earnings can pay for. Can support.
[00:57:55 - 00:58:41]
Guest A: Could very much support. Absolutely. Because you have to remember our NOI last year, and we didn't know this, you know, we didn't know how the year was going to go, but we made 1.2 million before you get into interest payments and being able to write off depreciation. So we felt like we had a lot of wiggle room if we brought that number down.
But if it was just 90% or 80% from a private institution, that number on their terms, you know, say they gave us seven years, they really thought we could make this happen. Yeah, I haven't calculated that math, but I would imagine that it's probably 4 to 6x per month, what we're paying right now, which would not have been plausible.
[00:58:42 - 00:58:47]
Host: And so what are you paying right now for your 25 year? 90% of $7.3 million.
[00:58:48 - 00:58:49]
Guest A: About $42,000 a month.
[00:58:51 - 00:58:55]
Host: $42,000 a month. Okay. Times 12 is half a million bucks a year.
[00:58:55 - 00:59:06]
Guest A: In my, in my head, before I got the final documentation, you know, we signed and everything happened. I was thinking that it was going to be between 450 and $550,000 a year.
[00:59:06 - 00:59:07]
Host: Yeah. Okay.
[00:59:07 - 00:59:08]
Guest A: In loan payments.
[00:59:08 - 00:59:33]
Host: Okay. I got a kind of bone up on my own sense of amortization schedules and how 5 and 7 and 10 and 25, how that changes the monthly payment. I don't really have a good sense for that. And then what of the.
So did you. The 40% SBA 504, the 50% conventional loan, did it come from the same lender?
[00:59:33 - 00:59:36]
Guest A: It did not, no.
[00:59:36 - 00:59:40]
Host: Why? Or did you try that? Or that was never in the cards or. Or what?
[00:59:40 - 01:00:30]
Guest A: Yeah, well, the SBA504 program had their own, at least in West Michigan, I think it's probably like this. And every city, you know, that they have their own point people that you go through. And, and so I was dealing with our Commercial banker on the private side, as well as the person who was running the SBA program out of West Michigan. Thankfully, West Michigan's not huge.
They knew each other. And so oftentimes I could have conversations where I could loop them both in, where I didn't have to have one, take down a bunch of notes, have another, hope they are on the same page. They understood what I was saying in both conversations. So it really, as we went through the process, it was like working with one group per se, where there was a leader on either side.
[01:00:30 - 01:00:36]
Host: And your conventional, your 50% conventional debt came from the bank that you were already banking with?
[01:00:37 - 01:00:38]
Guest A: No, I did not.
[01:00:38 - 01:00:53]
Host: No, no. Yeah. Oh, right. Because you were trying to get meetings and it was.
That's how you got the meeting. Great. Got it. Thank you.
Okay, so that is 90%. And then the 10%. Did you guys, you and Tim get together and bring $730,000 to the table?
[01:00:53 - 01:01:18]
Guest A: So we started having that conversation between the two of us and where we were both at, and if, you know, we were ready to make that kind of move and invest that much, you know, knowing that we had comfortable jobs that we enjoyed and things like that. And in that process, the sellers that were selling to us, the three, the main three that I typically dealt with, they were willing to sell or finance the other 10%.
[01:01:18 - 01:01:21]
Host: Did you ask them for that or did they sort of volunteer it?
[01:01:21 - 01:01:38]
Guest A: Volunteered to stick around, to show good faith, I guess. I'm not entirely sure, but those terms were completely negotiated between the five of us, you know, and they're not the same as what we. What you and I just discussed.
[01:01:38 - 01:01:58]
Host: The banks, your lenders, did they. Were they okay with the fact that this 10% was going to come, was going to be seller financed? Point being that you and Tim now are basically buying this $7.3 million business and piece of land for. With no money down.
[01:01:58 - 01:01:59]
Guest A: Yeah.
[01:01:59 - 01:02:00]
Host: No skin in the game.
[01:02:00 - 01:02:19]
Guest A: It gave us both credibility that I don't think either one of us realized would. In a different way. Because you had a group of people who own multiple businesses, who owned that business, who. Who oversaw that business, wanting to stick around in.
In the belief that we were the right people to sell to.
[01:02:20 - 01:03:08]
Host: Yeah. Despite the fact of what I just said, the SBA lenders, broadly, would love that you be the buyer of this business, or at least in terms of the ongoing operations of the business. Who better to buy a business than somebody who's already been running it successfully for six years? That ownership completely trusts and is basically going out of their way to sell to so you in in the person of you and Tim represent a huge risk mitigant from the lender's perspective because you're proven and so they, I'm sure they loved that as probably allow allowed them to get comfortable with maybe some of the less conventional stuff here like not having any, any money in it.
[01:03:08 - 01:04:13]
Guest A: It felt like throughout the entire process of research, initial offer back and forth, figuring out how to finance the more information that I was able to take in, the more I started to notice which roads were the ones to go down. And so as you explained I would not have thought that using somebody else's money to come up with the final 10% would have been beneficial in the eyes of a bank who was very risk adverse. You know, they want their money back. That's why they exist.
But throughout the conversations I had, the research that I did, the people that I've met, you know, and talked to, I realized that having seller financing was like a gold star on our year end financials which is you know, in the business world is like your report card, you know that you bring home to your parents like hey, you did well. You know what you're doing. You've really worked, you really worked in stock studied and everything went well. And that's what it felt like by the time I got all the information that that's what it felt like.
[01:04:14 - 01:06:10]
Host: Yeah, well lenders, SBA lenders definitely like and, and many of them insist on there to be there be some seller financing in the transaction because to, to the point it keeps. It's a demonstration that the seller has ongoing skin in the game and that they are incentivized to see a successful transition and that the business continue on. So, so, so it, it, it mitigates the risk that the seller is just dumping the business and high tailing it out of there. Now I've never thought that a 10% seller note is that incentivizing for somebody who otherwise just wants to peace out.
You know getting 90% of your purchase price is usually going to be enough for most people but anyway and maybe what they think is not you know, for the, for the totally unethical actor it's not going to do anything but for the person who is ethical it's just going to be that extra oomph that the seller needs to just do everything they can to make sure that the business is on, on good footing in the, in the buyer's hands. Sure now the, the but this the bank the lenders still need to when you have no skin in the game. You and Tim have no cash in this. They have to worry.
But these guys, what if it just. What if it does break? You know, what if the first year is a terrible season or whatever? What's stopping Kyle and Tim from just walking?
They haven't put any money into this. And the answer to that is, as you've already touched on a couple of times, this is your job. You're very specialized. Your skill sets.
It's not. It wouldn't be trivial for you to just go get a job as a GM in another golf course. So that's what's keeping. That's your skin in the game, that this is your.
This is your source of income and would be really hard for you to replace if. If the business hit on hard times.
[01:06:11 - 01:07:00]
Guest A: Yeah, I would agree with that. And I do think a part of it, too, was. And this is a credit to our lawyer. As we were going through the process was Tim and I signed a very lengthy operating agreement between the two of us about, you know, our roles, how we're going to operate.
And one of the big things that we made sure, because we. I think we wanted to prove to ourselves that we were buying it for the right reason. I knew why I was buying it, and I thought I knew why he was, you know, because I think I know him that well, and I believe he probably had the same feelings about me as well. But we put in writing that we wouldn't take any money out at the end of the year, like, as an additional bottom line, just like, hey, great year.
Way to go for five years. Oh, and that was just really. We did all that so him and I could feel like we were doing this for the right reasons.
[01:07:00 - 01:07:04]
Host: And what are the right reasons? Or better said, what are the wrong reasons?
[01:07:05 - 01:07:50]
Guest A: I would say the right reasons are to keep it what it is. It's a golf course. It's an unbelievable piece of land in a beautiful town, you know, and there's no other golf courses in. In Ada that the public can access.
And it. It's been here for. Since 1998, so 28 years. And so many people have gotten married there and had a corporate and charity fundraising outings.
You know, 45,000 golfers a year. The amount of people that use our practice facility and whatnot. We don't even track that. You know, add another 10,000.
There's a lot of people who know on any given day, if it's sunny and warm and they don't have anything to do, they can come out and utilize that space for the reasons they want to utilize it for.
[01:07:51 - 01:08:18]
Host: You know, hearing you talk, Kyle, there feels almost like mission to. To you here or a very strong why, as we put it, that you guys are motivated. You and Tim both are motivated. Those are the right reasons, I guess, that you are talking about, that you are motivated by what this place represents, what it means to people, all of the history that it has, the future, memories that it will create for the community.
That's extremely meaningful to you.
[01:08:19 - 01:09:45]
Guest A: Absolutely. Yeah. And to further cement that fact, you know, Tim is older than I am, so his son is in his 20s and he is following in his father's footsteps and unbelievably smart, great golf course superintendent in making, you know, going through the processes. We've already discussed that when Tim is ready to step back and retire per se, which if you knew him, he'll never fully retire, but his son is going to take over.
And I am very comfortable with his son taking over for Tim because he's so good at what he does. And so from Tim's perspective, you know, that's just another step to his legacy to his family. You know, knowing that I put in, say, 35 to 40 years by the time he retires, knowing that my son is going to take over. I have a daughter who's my oldest, and then I have four boys.
They're not of an age where they presented skill sets yet, where, you know, My oldest is 13, my youngest is 5, and so they have a lot of growth left to do. But in my head, I think that part of that is. Is there for me too. You know, one of my kids or a couple of my kids may follow in my footsteps and may eventually show the promise that Kevin is showing to his dad that, hey, they could take this over and run it for the next 40, 50, 60 years, however long people want to keep playing golf.
[01:09:46 - 01:10:20]
Host: Fantastic. The detail that you said a couple minutes ago, so you and Tim, between you in the operating agreement, agreed, codified, that neither of you would take out dividends, profits from the business for five years. So the only money you're going to see in your pocket is what you agreed your to your salary being as a W2 employee. Yep, as a W into employee.
And so the salary you guys were making salary before, obviously, as employees, and now as owners, all you're taking out of the business is your. Is your salaries. Is it the same salary as before?
[01:10:21 - 01:11:00]
Guest A: Yeah, within market lines of, you know, a successful golf course. And as they do. Well, one of the big things that Tim and I discuss often is how we can continue to elevate the other people that we count on. You know, while I oversee all the business operations of the golf course, he oversees all the grounds.
We are not the only people that are pouring their entire careers into making our golf course better. You know, head golf professional, food and beverage director, head chef. And so a lot of those people have been with us for a very long time, and we want to continue to elevate them as the overall golf course elevates as well.
[01:11:00 - 01:11:02]
Host: Kyle, you and tim, co owners.
[01:11:03 - 01:11:03]
Guest A: 50.
[01:11:03 - 01:11:05]
Host: 50, I think you said.
[01:11:05 - 01:11:05]
Guest A: Yep.
[01:11:05 - 01:11:15]
Host: 50, 50 is. Can be a dangerous split in a partnership. There's no tiebreaker. What if you disagree on something?
Did you guys consider that element here?
[01:11:15 - 01:11:55]
Guest A: We did. It was one of the first things that came up when we met with a lawyer drafting the operating agreement. And to Tim's credit, he said that we needed to have somebody who had the title of managing owner. So if there was some big decision and we could not agree on it, somebody had to be able to make that call.
And to Tim's credit, within maybe three or four seconds of the question coming out from our lawyer, he offered it and said that it should be me because I am in tune with the business on a daily basis. And so we both were kind of forewarned that it could be a complication as we were drafting this operating agreement. And it was one of the fastest parts that we went through.
[01:11:56 - 01:12:11]
Host: Great. Okay, so cap table, your splitsies, even 5050. But when it comes to decision making, control, if there is a disagreement, you have ultimate veto power, authority, or what have you. Great.
[01:12:11 - 01:12:12]
Guest A: Yes.
[01:12:12 - 01:12:45]
Host: All right, Kyle, Great. So we have unpacked the transaction in excruciating detail. Thank you for humoring me. You met, you.
You do the deal, you're in the business. Unlike most of my guests, whose lives are just turned upside down when they buy a small business and everything changes, and they show up on day one and it's a totally different environment, and they gotta drink from the fire hose. For you, it was probably seamless. You just came to work the next day as usual, only as owner this time, rather than employee.
[01:12:46 - 01:13:18]
Guest A: That is pretty much exactly how our first day on the new old job went. Nothing changed, really. As Tim and I have explained to several different people. Really, the only thing that changed was the name on the bank account of the operating company.
You know, and the fact that we had access to that in real time and we had to kind of watch it as it was growing and things were going out and coming in and things like that. Other than that, though, nothing has changed.
[01:13:18 - 01:13:21]
Host: You announced to the employees, I assume, or did you not even do that?
[01:13:22 - 01:13:58]
Guest A: We did do that. We tried not to announce to the general public because we didn't want, you know, greater West Michigan to, you know, form their own opinions. We want. We wanted to see how they were going to take any kind of changes that we might make.
Unfortunately, some of the news media outlets picked up on it and started running stories. And so we were able to make it about a month. I guess the good and the bad of that was the month that nobody knew that we had bought it. We were closed because it was winter, so nobody was thinking about golf anyways.
[01:13:59 - 01:14:02]
Host: Okay, okay, so when did you close?
[01:14:02 - 01:14:05]
Guest A: January 27th of 2025.
[01:14:06 - 01:14:19]
Host: Of 25. And you. So January 25. So you already told us how the business performed over the course of last year.
How did you do that? How were you able to basically improve performance in that first year?
[01:14:19 - 01:16:21]
Guest A: I think like anything, when it's yours, you get even more detailed and more focused on, you know, like on my end, there are ways where you can bid out different kind of contracts and services and things like that. Where I used to do that once every three years. I mean, it was one of the first things that I did on Tim's end. He started looking at the, the products he was purchasing and at what rate, and having conversations with different companies on better pricing, different products, things like that.
And then, you know, we just made little changes that have made massive differences. You know, we've started to introduce AI into our behind the scenes operations on a regular basis, which has freed up a lot of our staff to be more customer facing. Anytime you're in hospitality and people feel like they're somewhere they want to be, you know, they're more likely to come back, they're more likely to spend money when they're there. You know, things as simple as, you know, selling subscriptions to our range memberships instead of just a yearly free be.
Just. Just all these little things that, that we kind of always wanted to do, but they all required, you know, upfront capital. We're gonna have to ask for certain things and, you know, go through the whole process of is it worth it? They might say no, you know, they might delay.
We didn't have to have those conversations anymore. It was just him and I having those conversations. And so thankfully, a lot of things that I think were both in the back of both of our heads and we were just able to execute them. And we had a phenomenal Weather year, we opened early, we closed late, we had very little rain.
You know, we didn't lose any weekends, we didn't lose any Saturdays where you have bad weather. And in a seasonal business, especially one that's predicated around people not working when they play golf, you really need to kind of win the lotto per se, on a yearly basis to have a really, really good year.
[01:16:22 - 01:16:30]
Host: So in fact, some of the performance that you saw last year was that. And it's not gonna, you're not gonna get that every year. You're not gonna be so lucky every year, certainly.
[01:16:30 - 01:16:41]
Guest A: Yeah, yeah. We seem to be stacking a second year on top of the first year when it comes to weather, you know, but we still have another three months of our season left, so can't count our chickens yet.
[01:16:42 - 01:16:56]
Host: Yeah, yeah, A lot of little things you did over the year of 2025. But I also know you're planning bigger things. So what is some of the vision for. Call it the next couple next five years.
[01:16:57 - 01:19:14]
Guest A: So right now my main focus, Tim and I, is, you know, we came up with this idea in 2021, actually pitched it to the old ownership group and they liked it. But the investment up front was a little more risk tolerance than they were kind of willing to think about at that time for various reasons. Maybe they had already been discussing an exit plan at that time and I just didn't know about it. I don't know that.
But we started construction on a new year round indoor outdoor golf simulator building. So there'll be eight bays. In the winter, you can have the garage doors down and you can play simulator golf with a bar and a lounge and food as you could in any metropolitan area throughout the country. But it's on the other side of our range.
And so when the weather's nice, you can open the garage doors and still have that same experience. But you can hit actual golf balls down our range. You can watch the ball fly instead of hitting into a screen 10ft in front of you. And so we'll be the first of its kind in Michigan.
Um, I know that for sure. And construction I left there earlier today and the framing is, is, is going up and things like that. So we're about two months out. That'll really change the landscape of how our business operates because we'll have its peak season will be when people can't play golf outside.
So instead of making no money for four months, we will maintain, if not exceed our monthly expenses by having a building that will make money year round, plus heavy in the winter. And then down the road from that, you know, we have almost 30 acres of beautiful land inside the middle of our course with great views and ravines. We want to put a development in. We want to put in a new banquet center.
You know, just kind of modernize and have something where we can do things year round instead of seven months out of the year. So. And we knew all this going in before we bought it, that if we were able to take ownership and things went well, we were not reaching our cap. We were just starting the process of.
In my head, I think that we could double, if not two and a half times our yearly revenue in the next three to five years.
[01:19:15 - 01:19:22]
Host: Double, if not three times. So that gets you to a $10 million a year business, I think by 2020.
[01:19:22 - 01:19:32]
Guest A: By 2031, 2032, if we're able to do all the things that we want to, you know, the market dictates it. I think that is well within the realm of what we could do.
[01:19:32 - 01:19:39]
Host: And I'm hearing the banquet suggest that you think that there's. That there's more to be had in the event part of your business.
[01:19:40 - 01:20:38]
Guest A: Yeah, because we. We have. It's. It's a.
It's a structure, but it's a tent. You know, it's not a graduation tent post like you put up in a day and take down in a day. You know, we have a building with bathrooms and a bar and a kitchen, but the actual space where people sit down and eat and whatnot, that is a tent structure. And so you can only have events in there when it's warm enough.
So our season typically runs May 1st through October 15th. And if we were able to put in a year round where we could have acknowledged we could have heat in the winter, you know, with the amount of high schools and teams that play at our. At our golf course and local colleges. And I think that we could probably double our weddings, we could double our graduation parties, and we could probably have.
Where we might do four or five community events like a football rally, something along those lines. I think we could probably do 20 to 30 of them a year. I think we could. We could probably 3x our events while charging more.
[01:20:39 - 01:20:43]
Host: And Kyle, where is all of the money coming for these capital expenditures?
[01:20:43 - 01:21:43]
Guest A: The hope is, is that we just self fund them at this point based on the success of the golf course. We didn't take out any private money from anyone to build the building we're building right now. We're funding it as we go. And that seems to be the model.
It's worked now, and I'd like to thank, within a year, year and a half to put a development in. We could fund that ourselves and then sell off the lots instead of partnering, partnering with a developer that may want, you know, 65 or 70% because they're going to put in the road and, you know, the curbing and the street lamps and things like that. And so that's how we envision this going moving forward, is we do one thing, it changes the structure of how we operate. We have more cash coming in on a regular basis.
We divert some of that into the next process, go through it, and all of a sudden we had the same loan structure we had when we first bought the place, but we have three or four new profit centers that we didn't have.
[01:21:43 - 01:23:07]
Host: Yeah, I'm seeing a guy or two guys, you and Tim, who own this, call it $12 million piece of land. Although, because you guys are never going to sell the land or develop the land unrelated to Quail Ridge. That number that I keep fixating on is kind of irrelevant because it ain't ever going to be sold, at least not in your lifetime. But, you know, it's notable, you know, on your net, your net worth, it would count the market value of that land.
So two guys who bought $12 million, you have $12 million of land or, you know, $7.3 million, business, however you want to slice and dice it, didn't put in any of their own money and have a 25 year amortization schedule on this. After their first year of ownership, things are going really well. Second year looks like it's going to be good as well. Have all of these opportunities to create new sources of revenue from in this business, none of which will require financing, all of which can be funded from the cash flow of the existing business.
Are you psyched about this? I mean, this is a kind of a crazy outcome for you and Tim?
[01:23:08 - 01:24:51]
Guest A: Very much, yeah. Absolutely. It's one of those things where until you do it, you don't have the proof that you can do it and it's going to work. I know, speaking from my perspective, that I've felt like I could run any golf course at any time since I was in my mid-20s.
And I've certainly learned a lot since then. And I've continued to grow and expand what I know and how I can operate. But I had a pretty core belief in myself that a long time ago, ago, I could do this for the rest of my life better than anyone I've ever Met. And so this is just further cemented the proof that I've seen it happen now with ownership, and not just in two months or four months, but almost two full golf seasons on top of my career before that.
And so really, the only thing that's changed in my mind is I want to continue to do it outside of the golf course I already own. I want to continue to buy, accumulate, show other people how to run, you know, go through the process of negotiating down to a price that is worth buying something profitably to make it profitable right away, and just accumulating real estate along the way with operations that are successful. You know, ADA will always be my home. I will always be based out of here.
My kids are far too young for me to go anywhere for anytime soon. But at this point, with technology and, you know, zoom and things like that, you can operate almost anything from anywhere as long as you have the right people in place to do it.
[01:24:51 - 01:24:57]
Host: And so did I just hear golf course roll up? Is that what you just said to me?
[01:24:58 - 01:26:22]
Guest A: I would like to see how it goes. I would like to continue to explore what's out there and meet people that maybe, you know, have three or four golf courses and how they went from one to two and how they continue to go on and, and seek out new properties and what they learned and the negotiations that take place. And because, you know, if you're looking for them, you can see a golf course for sale at any given time somewhere in the country. The problem that I have and most people have when they see that is they don't know what that operation looks like.
They just know what the seller wants to sell it for. I had inside information because I ran the place for so long. I was in charge of the numbers. I was in charge of making the business run.
So I knew what I was buying exactly. But now that I see that, you know, there's golf courses that pop up for sale, I see an initial price, and it's like, well, now I want to know more. Is that business successful? Does it operate at a good level?
Does it have a lot of deferred maintenance? Is there, you know, was it one or two people who owned it and aged out and stopped putting money into the. Into the place 20 years ago, and you're going to buy something that you have to put new roofs on and H Vac in and replace the golf carts and fix your irrigation and, you know, those are all the things that, like, I can't stop my mind from wandering and wanting to know more.
[01:26:23 - 01:26:36]
Host: Yeah, yeah. No, Understandable. Well, but I assume that any visit you, you would make in person to these golf courses, you could quickly eyeball a lot of this stuff and, and come to some quick conclusions.
[01:26:36 - 01:26:38]
Guest A: At this point in my career, I believe that. Yeah.
[01:26:40 - 01:27:50]
Host: I gotta say, Kyle, you know, when I talk, talking to you makes me a little uncomfortable because in our world, most of my guests are buying businesses in industries that they are new to and they are fully expecting to again, drink from the fire hose. Steep learning curve. It's going to be, it's going to be, you know, an intense year, first year or two or three, to learn the business and the industry. And we, we accept that risk.
That's part of this, this path. But when I talk to people who buy businesses and know the industry so well, or in your case, you were an employee, you were running the place, own the place, and just what an advantage that is. It, it just, it reminds me of how difficult the normal path of a typical guest is where, you know, you're buying a plumbing business and, you know, you don't know much about plumbing. But hey, that's what, as I said, that's what this path is for, for, for most acquiring minds, guests and eta entrepreneurs.
Yeah. Any last thoughts, Kyle?
[01:27:51 - 01:28:44]
Guest A: I would say that I understand where you're coming from, where people buy businesses that they don't know anything about. And I, I agree with that. And in that way, I was fortunate and Tim and I were very fortunate to buy business that we knew all about. We had just spent so much of our lives, our adult lives, post college, learning how to run our area of the business to get to a point where we could buy one and know that we could be successful at it.
You know, so other people may have done that in a different path for, you know, four or five years and accumulated some wealth. And they just said, I want to diversify and I want to, I want to get this, I want to get that. And I'm going to go through the hardships of not knowing what that industry was like. Our hardships happened while we didn't own it.
Our learning curve, all that happened when we, when we did not have what we have now.
[01:28:45 - 01:29:09]
Host: Okay, Kyle, well, we will link to your LinkedIn, we will link to Quail Ridge so the golfers in the audience can go ogle your beautiful, your beautiful golf course and maybe pay you a visit. And we thank you for your time. Really interesting story and congratulations to you. Congratulations to Tim.
Tell him we said so. This is really an epic turn of events for you guys.
[01:29:09 - 01:29:15]
Guest A: So congratulations yeah, well, thank you, Will. And thank you for giving me the time to come onto your podcast. It's been a pleasure.
[01:29:16 - 01:30:00]
Host: Hope you enjoyed that interview. Don't forget to subscribe to the Acquiring Minds newsletter. We send an email for every episode with an introduction to the interview, a link to the video version on YouTube, and soon, key takeaways, numbers, and more essentials from the interview. For those of you who don't have time to listen or watch it, subscribe at Acquiring Minds Co.
You'll also find all our webinars there on the website, both those we have coming up, and recordings of past webinars. At this point, There are over 30 webinar recordings, a wealth of information on all the technical nitty gritty of buying a business. Acquiring Minds Co.