[00:00:00 - 00:04:59]
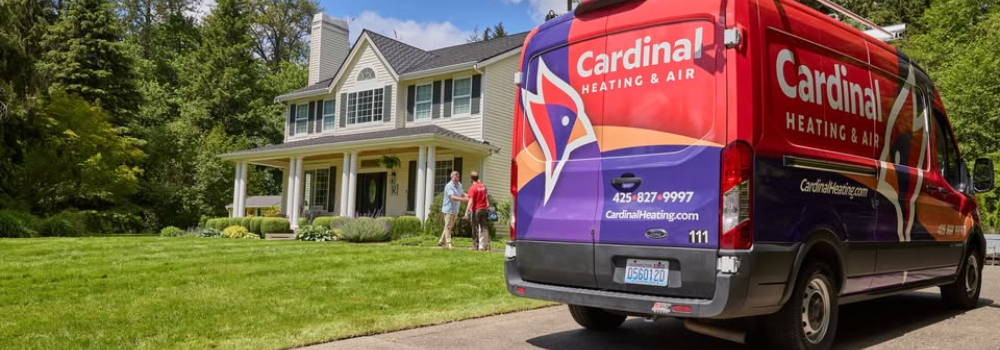
Host: Most people in our world strive to buy a business that works. Today's guest bought one that was not working, and he did so on purpose. Mike Bourgeois and his search partner acquired Cardinal Heating and air in Kirkland, Washington in December, a business doing 12 to 15 million in revenue but losing about 3 million a year. And that combination is the whole thesis.
The demand side was fine. The problem was cost structure. So Mike could underwrite this the way a deep value investor would if it worked. A million plus of EBITDA within a couple of years.
If it didn't, they could probably liquidate the assets and roughly break even. Heads I win, tails I don't lose much. We rarely hear this story on acquiring minds. First time searchers seek healthy, profitable businesses.
That's what the playbook says to do. And it's what SBA lenders underwrite. So today's conversation with Mike is a chance to think about risk and opportunity a little differently. The conventional acquisition looks safer.
Real earnings, a clean Q of E. But you pay a price that assumes those earnings persist and you personally guarantee the loan. If they don't. Mike Steele inverts that.
Everything he had paid in cash, but no bank debt and no personal guarantee. What he took on instead was the operational chaos and the chance of losing it all. A different shape of risk, not less of it. Here he is, Mike Bourgeois, CEO and co owner of Cardinal Heating and Air.
You've heard it plenty on Acquiring Minds that the deals you walk away from matter as much as the ones you close. What gets talked about less is what walking away actually costs. The deposits, the legal and Q of E fees, the months you'll never get back. Well, in a webinar this Thursday, a panel of Acquisition Lab members will unpack deals they came very close to acquiring but ultimately chose to leave behind.
Moderating will be Tim Erickson, COO of Acquisition Lab and a former guest on this show. Topics to include the moment each buyer realized the deal wasn't the right one, what diligence uncovered and how it changed the story what walking away actually cost in deposits, in fees and in time how the buyers view these decisions with the benefit of hindsight, what they looked for afterward and what they eventually acquired. Expect candid stories about the signals that made the decision clear and why passing on the wrong business can be just as important as finding the right one. The webinar is the deal I almost bought and why I passed.
And it is this Thursday, September 10th, noon Eastern. Link to register is right at the top of this episode's show. Notes or on the Acquiring Minds homepage. AcquiringMinds Co.
Welcome to Acquiring Minds, a podcast about buying businesses. My name is Will Smith. Acquiring and existing existing business is an awesome opportunity for many entrepreneurs and on this podcast I talk to the people who do it. Buying a small business sounds simple.
Find a company, due diligence, Get a loan close. In reality, you wear every hat just to get the deal done. And then the moment you close, you have to throw those deal making skills out the window and learn how to operate. You shouldn't have to rebuild this infrastructure from scratch and you definitely shouldn't do it alone.
That's why Walker Deibel created Acquisition Lab, which started as an accelerator, has expanded into a complete ecosystem for acquisition entrepreneurs. Over six years, the lab's 1200 members have acquired over a billion dollars in businesses. The lab puts everything under one roof, an active community, deal reviews, post close services, and a dedicated fund helping experienced operators buy larger businesses. If you're serious about buying a business, come see why Lab members have a 40% success rate.
Learn more in the show notes or at acquisitionlab.com/acquiring minds Mike Bourgeois welcome to Acquiring Minds.
[00:04:59 - 00:05:00]
Guest A: Thanks for having me.
[00:05:00 - 00:05:38]
Host: Will Mike, you reached out to me after hearing our interview with Dan Burnside from earlier this spring. Dan bought an H Vac business and the wheels came off quickly after he got into it. It's a brutal story. You said that you heard a lot of patterns familiar from your own experience.
In your experience H Vac acquisition. The difference is that you bought your business in distress. Intentionally so. Yours is the story of a first time searcher buying a distressed business.
A pretty uncommon pattern. We're eager to hear about it. Let's begin some background on you. Please to start.
[00:05:38 - 00:06:18]
Guest A: Mike of course, of course. I am originally from the Boston area. I was in California for my military service. I was in the Air Force for eight years, got out, worked in finance a bit and really started in taking search seriously in early 2024.
My partner and I we were searching for about a year and a half. Seriously. We came to our acquisition, Cardinal Heating and Air in November of 25 and we had a 30 day diligence period and closed it in December of 25.
[00:06:18 - 00:06:26]
Host: Great. And Mike, just give us a little bit more on why you decided to search. Why the path of ETA was the one you chose out of the military.
[00:06:27 - 00:07:15]
Guest A: Good question. So I decided to pursue search because I've always been entrepreneurial. I like challenges. I could have stayed in the military and done 20 years, probably commissioned as an officer and had been successful there.
But I just really like seeing how far I can take things. And I love finance. I'm a big deep value investor. And so combining kind of the military with the finance, it has a natural conclusion to come to search.
I initially found out about it so one of my close friends bought a payments processor actually when I was deployed and during kind of the trough during COVID and turned around and sold it two years later for quite a bit of money. And so I'm like, okay, this could be a really viable career path.
[00:07:15 - 00:07:38]
Host: And the profile of that former military buying a particularly a trades business is one that we see a lot. Are you, did you have a background that gave you the leadership skills, the, the kind of operational chops that that is so often that comes from that military experience or are you not that profile necessarily?
[00:07:38 - 00:08:16]
Guest A: I would say what makes me different is I do feel like that profile skews very heavily towards commissioned officers. I wasn't a commissioned officer, I was enlisted, so I would say that's probably one difference. But overall I ran one of the larger medical practices in the Air Force, the cardiovascular clinic at David Grant Medical Center. It's a lot of organized chaos because we see saw up to 10,000 patients a year in some days.
So I, I like to say I pretty much handled everything that was non actual medical care, all the administrative work, all the office work. So I would say to some degree, but maybe not as in depth as a commissioned officer.
[00:08:17 - 00:08:28]
Host: Okay, and then the parameters of your search, when you embarked on the path, what were you looking for? I don't think you were looking for distressed at the outset. We'll get there. So, so what were you, what were you looking for initially?
[00:08:30 - 00:09:06]
Guest A: Something that's given me less brain damage for sure. I would say non discretionaries, million plus in ebitda, not really tied to Mary to any specific geography, but really just non discretionary and the ability to really create value. And so what I mean by non discretionary, anything that's always going to be needed, that might not be really impacted or kind of taken away by AI so H Vac. It's always going to be needed in one form or another.
And I think we're a little bit away from robots doing installs, so it made sense.
[00:09:06 - 00:09:22]
Host: Yeah. Great. And you're geographically agnostic, truly, because you're from Boston. You said you, I believe that you started your search while in California.
Yes. You're now in Kirkland, Washington, as we'll hear. So you really were prepared to go anywhere and did in fact go anywhere?
[00:09:23 - 00:10:01]
Guest A: Yes, yes. So I really Just I had zero desire to be. Well, of course if I could choose California or Florida versus Alaska, I'm choosing California or Florida, but just really just wanted to go wherever the opportunity is. And it's difficult doing an industry completely geographic agnostic search.
But I just felt like just given so the other side of the non discretionary and the trades, it's almost a commoditized search landscape so everybody's looking at it. So I felt like we couldn't really be picky in where it is if when we found something great.
[00:10:01 - 00:10:11]
Host: And then the partnered aspect of this you did ultimately acquire with a partner. Did you say that you set out with a partner or fill that out a little bit more?
[00:10:11 - 00:11:11]
Guest A: Of course. So my, my search partner and I, we've been friends since 2021. We actually met at one of Karen Spencer's hosted events in San Francisco and we hit it off and we actually didn't really discuss searching together for about a year. And when we actually decided to really start looking in 2024, that's when we decided to partner together.
We're like, hey, we have a lot of complimentary skill sets. We both have some finance background. His was more at a hedge fund and I did work at a very small independent sponsor in a small family office as well. But I have, I'm definitely more on the operations and he's more on the, the math.
So we have about 80% overlap. But we just said hey, we can put our heads together. And the other aspect of it, it's, it's been really, really great having somebody to be supportive. We've both had to be supportive for each other at different points in times, especially post acquisition because it's not, it's not easy.
It's definitely not easy.
[00:11:12 - 00:11:28]
Host: Yep. We're gonna want to hear a little bit more about how you have supported each other and the value of having a partner once you're in the business. But for now, let's carry on with the plot and your discovery of this distressed H Vac business.
[00:11:28 - 00:12:15]
Guest A: Of course. So I found it initially from a veteran ETA networking. It was slack. And this gentleman posted saying, hey, I.
My family member, he owns a H Vac company in Kirkland, Washington. It's a distress situation. We believe somebody that has a military background would be well suited to handle the brain damage, as I like to call it, the kind of intense, the daily intense. A lot of the low hanging fruit, a lot of the fixes.
And so they weren't looking for a private equity shop or somebody else to come in they were looking for a military searcher.
[00:12:16 - 00:12:17]
Host: And why was that?
[00:12:18 - 00:12:36]
Guest A: Again, I think it's the background. The background and the ability to handle high levels of stress is the reason why they were looking for military. Somebody with a military background. That's at least what they say.
And so I had a few conversations with this person and got connected with the owner and we negotiated from there.
[00:12:37 - 00:12:47]
Host: And when you say owner, the owners were not the founders of the business. Small business owner operators. This was already another group that had acquired the business.
[00:12:47 - 00:12:50]
Guest A: That's correct. That's correct. They weren't the original founders.
[00:12:50 - 00:13:23]
Host: They weren't the original founders. It was another, you know, kind of investor group and they were looking to divest it, divest themselves of it. Great. So we can guess that the reason that you would take on such a challenge is that the price would be right.
So I guess probably always in the case of buying distressed assets, you're able to get them at a price that's, that's so compelling that it overcomes the, the, the obvious risk of buying something that's malfunctioning.
[00:13:23 - 00:13:24]
Guest A: Of course.
[00:13:24 - 00:13:35]
Host: So, so give us, give us more about the picture here, whatever you can say about the, the size of the business or the price. I know some of this stuff is sensitive, but tell us what you can about the shape of this deal. Sure.
[00:13:36 - 00:15:19]
Guest A: So again, I probably wouldn't in 99% of cases not suggest somebody pursue this. But it was a non exclusive loi. There were a few other competing parties. We happened to just be first because we had a great lawyer and we moved with a lot of speed and frankly, because of the characteristics of the business, the QOV is not going to tell you very much because it's, it's losing money.
But as far as the actual, the way we structured the deal and our thoughts on it is even, even today we, we did raise a little bit of money, which we could talk about later. But it's really a Monica's Provis principle of heads I win, tails I don't lose much. You know, honestly, it's, it's true, it's true. We, we could have gone in with week one and liquidated the company and recap most of what we had spent on the company, frankly.
And just for your knowledge, distressed companies, either depending on how they sell or how they're structured or who they're selling to, they either sell as a percentage of revenue or they'll sell as a projected like a strategic carve out. So if you're a firm buying another firm and you buy a Distressed H VAC company or just using that, for example, you can essentially carve out all the redundancies. And that projected ebitda, they'll give you a discounted multiple of that. But we bought the company based off of that.
I can't really give too much insight to the structure or the price, but it would be essentially 1x of what our projected first year EBITDA would be.
[00:15:20 - 00:17:03]
Host: If you ask owners in the ETA and search community which insurance broker provides highest quality work, great outcomes and has a practice dedicated to searchers and acquisition entrepreneurs, one name comes up again and again. Oberle. Oberle Risk Strategies has worked with hundreds of searchers over nearly a decade and is in fact led by a two time successful searcher, August Felker, which makes Oberle a specialty insurance brokerage for searchers, by a former searcher. And if you've got a business under loi, Oberle will provide complimentary due diligence on that business's insurance and benefits program.
An easy, no risk way to get to know August and the team at Oberle. To take advantage, check out oberle-risk.com that's O B E R L E- risk.com link in the notes. But I feel like, you know, what we as business buyers do is not give the seller credit for what we're going to do. In other words, we're buying historical ebitda, we're not buying the EBITDA that we ourselves see hope to generate.
How do you come up with the projected EBITDA number? And, and, and what's to stop you from just sandbagging the number? Like oh, you know, I'm, this is going to take three years to get back to break even. Therefore I'm paying zero for it.
So you know, I mean, I just, when you don't have hard number, hard historical numbers to look at and you're in, you're negotiating on what might happen in the future, it just seems even squishier than these acquisitions often are.
[00:17:03 - 00:17:42]
Guest A: It does. So, so to give context, I misspoke. So it, it was a little bit of that, but it was also primarily liquidation. Value is what we had made our decision.
It's like, hey, if we just say, hey, this isn't working and we sell the entire company, how well do we do? And it's essentially break even. So it was, I would say probably 20, 30%. We do everything right.
By end of year two, we could have a positive one, one and a half million EBITDA or company fails. Well, I don't want to say fail, but we sell the company for parts and we at least break even.
[00:17:42 - 00:17:49]
Host: That's a really compelling proposition. A very. Mohnish Pobrai, what was it? Heads I win, tails I don't lose that bad.
[00:17:49 - 00:17:51]
Guest A: Tails I don't lose that much.
[00:17:51 - 00:17:52]
Host: That much.
[00:17:52 - 00:18:11]
Guest A: He's a big Buffett Munger investor. So am I. So it's a very, I mean that's when we're looking for any sort of acquisition or any sort of capital allocation where just does the risk adjusted return just beat either the hurdle rate and then if it doesn't go well, how bad are we hurt? And so we always try to minimize our downside.
[00:18:12 - 00:19:06]
Host: Yeah, it's funny, Mohnish Babrai is not a name that has come up. I'm not sure he's ever come up, but it just came up in my last interview with Sujith Shankar, who will air just before this one. So Mohnish is in the air and, and Mike, in fact, when you put it that way, that even if you were to sell the business for, you know, parts, to put it crudely, you could recoup your investment, then it almost starts to seem like a really competitive, a really competitive opportunity. In other words, that the price would be driven up by other interested parties from such a low, a low price.
Did you was there and you had a non exclusive loi. So it sounds like they had freedom to just shop the deal around anywhere they wanted. Even after you were looking serious, seriously at it and diligencing it. How did all that play out?
[00:19:07 - 00:19:43]
Guest A: Good question. So it was purely, I can't speak too much to their situation, but it was timing. All I can really say about that is timing was of the essence. So it wasn't really a matter of them trying to sell it for as much as possible.
They just wanted to get it off of their books by a certain time. And so speed opposed to price was really the determining factor. So we were just the fastest when we decided, hey, we looked at this, really realized, okay, this makes sense and we pursued it from there and we were like, we're just going to be as aggressive as hell.
[00:19:45 - 00:19:54]
Host: I heard you say that, you know, if you, if you flip the coin and it comes up heads, you have the opportunity here of getting it to a million, million and a half of ebitda. What was that based on?
[00:19:55 - 00:20:28]
Guest A: Historical revenue. So historical revenue has been sitting between 12 and 15 million in, in top line, obviously not accounting for the gross profit and then the negative EBITDA. Normally H VAC companies are say 8 to 12. Best player will be maybe 15 in a really good month, maybe 18%.
But just assuming we hit 12 to 15, just say 15 and top line. And we have good margins, not great margins, just okay margins. We could do a million, million and a half.
[00:20:29 - 00:20:36]
Host: Great. Okay. And so did you say it had been at 15 million or did you say 12 to 15?
[00:20:36 - 00:20:43]
Guest A: At its highest peak, I think it did closer to 16. But it usually heads ping pong between 12 and 15 million depending on the year.
[00:20:44 - 00:20:52]
Host: So even when you were looking at it, was it still sitting at 12 or 15? Between 12 and 15, yes. Okay, so it wasn't a demand problem, the revenue was there.
[00:20:52 - 00:20:52]
Guest A: Correct.
[00:20:52 - 00:20:55]
Host: It was a margin or expense problem.
[00:20:55 - 00:22:33]
Guest A: It was a margin and expense problem and it was also a cost structure problem. So one of the biggest things that we did, obviously you're looking through the entire funnel and the entire process and getting an understanding of how information flows from, you know, the, all the, all the way in the front end on the GBP to all the way in the back end to the collections. And there were just little low hanging fruits all across the chain that were broken. But one of the biggest ones were pricing.
So this isn't a trick question, but when you have a part for that you buy from your vendor, you shouldn't be charging the customer less for it. So there are little cases like that where just pricing hasn't been, you know, in some cases it hadn't been increased in, you know, pre Covid. So and it wasn't that the previous owners were bad, it's just that there was, I think that there just needed to be somebody here present with a lot of oversight in order to keep those, those changes, those incremental changes and those checks going. But a lot of it has been driven by just price increases.
Not even necessarily charging a premium, just charging industry standard, watching the estimating, making sure that, you know, we don't excessively discount and getting those controls in place. So at our lowest month, well, not our lowest month, but the lowest month, the gross profit for the business was 7% and an average month was about 15 to 20%. And you know, last month we hit 48, and this month we'll hit probably 48, 49%. So it's still not necessarily great for H vac margins, but they're definitely a heck of a lot better.
[00:22:33 - 00:22:42]
Host: Congratulations on that progress from 7 or and then 15 ish all the way up to 48. And what should gross margins be in a healthy H Vac business?
[00:22:43 - 00:22:51]
Guest A: It depends. So for your, if you're very service heavy. You'll be closer to 55, 60% install is going to be closer to 50, 48, 50%.
[00:22:51 - 00:22:55]
Host: Okay, so you're starting to edge into healthy territory.
[00:22:55 - 00:22:55]
Guest A: Yes.
[00:22:55 - 00:23:08]
Host: Good for you. So back to how all of this mess happened. Understanding that it's again that there's some sensitive stuff here, but essentially the business was under managed for a while.
[00:23:08 - 00:23:09]
Guest A: Correct.
[00:23:10 - 00:23:33]
Host: Because it couldn't be selling parts at a loss, et cetera, over years and grow as it had. So to get to 12 and 15 million, bouncing between 12 and $15 million a year of revenue, that's a sizable business, sizable H Vac business. So at some point in its history, it must have been doing things correctly. It sounds like in the most recent chapter it had just been undermanaged.
[00:23:34 - 00:24:22]
Guest A: Yes. In the last two years it's been under managed, so previously it was doing as much as 2 million in EBITDA. So it was a pretty decent sized operation. And I think that's primarily, it's just a lack of oversight and direction.
There's the business, it's completely even just from a culture standpoint and how people outlook, it's completely changed from when we took over to now. I mean, obviously things aren't perfect yet and we're still getting there and going in the right direction, but it was just a lot of improvised jazz and people were just trying to do whatever to make the business successful. And I think it's just from having a lack of direction is what really caused the business to go downhill initially.
[00:24:22 - 00:24:35]
Host: Yeah. Yeah. Great. Well, we're going to hear about all the things that you have put in place to turn things around.
How many employees were there? We haven't gotten that. That'll give us the best sense of scope here. Scale.
[00:24:36 - 00:24:41]
Guest A: So we currently have about 55. At its peak, the company had 72.
[00:24:41 - 00:24:46]
Host: 72 down to 55. And when you bought it, it had 72.
[00:24:46 - 00:24:50]
Guest A: It had 61 when we, we bought it. Yeah.
[00:24:50 - 00:25:21]
Host: Mike, let's turn back to the risk just before we get into actually doing the deal. I know you can't be specific, but give us a sense, if you could, of what the financial risk was for you personally. Was this everything you had on the line, not something in between, I assume if, if it's distress, there was no sba, were there investors? Tell us what you can and specifically about the real financial risk that it, that it represented to you personally.
[00:25:21 - 00:27:13]
Guest A: So it was an all cash deal. When we initially bought the business, my partner and I, we put about pretty much everything into working Capital to, to get it up and running. And so there definitely is that financial aspect of the risk. And then two is we did raise a little bit of money in February to recap because it's very hard to get a line of credit on a distressed business.
So we raised a little bit of money and we have a good chunk of working capital, but it would pretty much wipe me out if it went to zero and we couldn't recoup. So the projection is if we sold everything for parts, we would mostly break even. That's true. Of course, the investor has to make whole as well.
So there is a lot of financial risk there. And to give context, it isn't straight equity, it's a debt instrument. So it's not like we're splitting the proceeds evenly. But there is definitely a high level of mental stress and psychological risk.
I mean, a big part of this has been winning over the team and undoing a lot of the processes for the team and a lot of the things that were impacted from a culture standpoint. But it definitely hasn't been easy. Maybe definitely not as easy as I've made it sound. Because I mean, just even getting that information to know that we have to do price increases, it was hours upon hours of getting basically broken and mismanaged data, organizing it and then actually being able to go and do comparisons and then figuring out it wasn't like a 12 day process.
It took us months to figure that out.
[00:27:14 - 00:27:21]
Host: When you said a debt instrument. So what that means is that there is debt on the business.
[00:27:21 - 00:27:23]
Guest A: Yes, there is, but.
[00:27:24 - 00:27:29]
Host: Okay, but, but it's not just straight, a straight loan. It's flesh that out, if you would.
[00:27:29 - 00:28:52]
Guest A: It's essentially in trenches. So we have two tranches of debt. And so the first tranche is just for closing the debt. That's a debt instrument.
The second tranche is actually equity, but it's contingent on us hitting a certain percentage of profitability and then we get it automatically. So that gives him. It's beneficial for him because obviously he gets preference. So he's on top of the capital stack because there's no acquisition debt.
So he'll definitely be be made whole. But it's also good for us because it allows us to get that we otherwise wouldn't be able to get on the business. And we use that purely for growth and working capital. Essentially just additional Runway.
Because the other part is when we took over, even just our cash, when it was burgering money, even the cash that we injected was only weeks worth of Runway. And so we had to pull a lot of levers besides just raising money. We had about an 800-900-k AR balance we had to aggressively collect on that just was sitting there. We negotiated with vendors.
It was not easy at all to do. And so even, even now it's honestly, I'm a little bit amazed that we've been able to stretch it out eight months because we took on, I mean, if everything was steady state, we had about three weeks of cash when we took over.
[00:28:53 - 00:28:57]
Host: Wow. Okay. And back to this debt instrument, this convert. It's a convertible note.
[00:28:58 - 00:28:58]
Guest A: Yes.
[00:28:58 - 00:29:06]
Host: And so essentially it acts as debt and then so from the investor's perspective, that's providing some downside protection.
[00:29:06 - 00:29:07]
Guest A: Yes.
[00:29:07 - 00:29:46]
Host: As well as, as well as it's, it's earning a return immediately. So there's sort of a floor to the return. And then it's got great upside because it converts to actual equity to a percentage piece of the business in a happy upside case. This is the second time that the convertible note has come up in a few months.
Justice Ludig, who bought an H Vac business in Texas, also had one. So, so I. Makes me wonder if this is something that's being used more and more just a coincidence. I know you don't want to name who your investor is right now.
I think you're planning to do that later, but it is an investor from the search community.
[00:29:47 - 00:29:52]
Guest A: Yes, he is a well known investor in the search community.
[00:29:53 - 00:30:32]
Host: Okay. I thought when I, when I, I would have guessed that maybe somebody who invests in a deal like this because it's so unconventional for searchers, that it would also be an unconventional investor. So interesting that it's a, an investor who's very active in self funded search and you, a self funded search, are both agreeing that this opportunity could make sense for a searcher, unconventional though it might be. So we'll have to see if more deals like this start happening.
Just this Slack Channel. Mike, for eta, it's, it's vets who are in eta, Vets who are in search. Is that something that can, you can share or is that kind of invite only situation?
[00:30:33 - 00:30:40]
Guest A: I think it's, I don't know if I can share it. It's just Charlie McCarthy's veteran ETA network.
[00:30:41 - 00:31:39]
Host: Okay. So the overall situation is that you have this largest H VAC business that is doing between 12 and 15 million dollars of revenue even under distress. So it's still generating historic levels of revenue. It's been as many as 72 employees.
When you're looking at it, it's 61, 62. And it just feels like it's been under managed. You see opportunities where you can fix things. So it feels like as we kind of talked about in the pre call, it wants to be fixed.
It wants to be like somehow like naturally get to a higher level of profitability than the $3 million that it's bleeding every year. It's almost like it's in an unnatural state and your job is to return it to where it wants to be. So it's not shedding employees and it's not shedding customers, right?
[00:31:40 - 00:32:43]
Guest A: No, no, not at all. We have a pretty active client base. We have 22,000 historical customers. I would say that in the two years, was the operationally, was the reputation hurt?
Maybe a little bit, probably, yeah. But it's still, it's one of the largest independently owned H Vac companies in Kirkland and it still has a great reputation and it wants to do a lot more. I mean, even, even now we're pulling some levers to get more leads and installs on the board, but it wants to do more than 15 million in revenue. It wants to do 18, 19 million.
So I mean we're, we're pushing it to do that. But I would assume, I would, I very much agree with you. It was very much a natural, I would say sick state. And I'm not saying I'm a doctor or anything like that.
I'm not. But it's just, we're just doing everything we can and we're learning every day. We're definitely not experts at this, but we're working very hard to get it to its steady state.
[00:32:43 - 00:33:25]
Host: Yeah. And so that was the business itself. And then your structure to buy the business was a significant outlay of cash for you, but in the grand scheme of things, not a lot. You thought that if things didn't go well, you would be able to recoup at least your investor's investment, if not your own investment.
Actually, if things went poorly, if things went well, this is the opportunity to own a 12, 15, maybe 18, $19 million a year h Vac business at an entry price that was frankly negligible in the grand scheme of things. Pretty, pretty interesting opportunity.
[00:33:25 - 00:33:25]
Guest A: Okay.
[00:33:26 - 00:34:01]
Host: And by the way, I would also feel like the question of transition here is more interesting than our typical. Because if it's being under manage, I would suspect. Well, I could take this a bunch of ways. I might think that the morale is low, even hostile.
On the other hand, it might be to our point about like the business wanting to get Back to steady state. It might be an employee base that's eager for a pro, for some proper leadership and that they welcome somebody who's going to come in and try to fix things. So in fact, what. What did you find?
[00:34:01 - 00:36:03]
Guest A: So I'll start with where we're at today. I would say that culturally the business is much stronger. We still have a little bit of friction and there's still some areas where we're improving, but we're definitely working more together as a team. When we took over, we were actually pretty welcomed.
I think it was a breath of fresh air because there was a lot of questions of like, hey, is this business going away? Where are we going? What are we going to do? And so it was initially some.
There was definitely an initial welcome. I do think my partner and I have made maybe some missteps along the way, but we're doing everything that we can. But what I'd say it's been overwhelmingly welcome. As far as the transition is, there wasn't really one.
So we flew here on the 7th, got to our hotel on the 7th. On the 8th, the morning of close, we were at a coffee shop waiting for everything to be closed, all the final documents, everything like that. Got celebratory coffee. Then we drove over, we spoke to the gm.
He would fly back and forth every month, gave us tour, shook our hand and said, good luck. So there was zero transition. We just got thrown into it. And then later that day, we, we, you know, my partner and I are now talking in front of 62 people that we've never met before.
We had zero, nothing prepared. And so it was definitely. We were just kind of thrown into it and just said, hey, good luck. And so there was no, there was no transition period.
I would say that the reason why we've been successful, it's probably 10, 15% of us and it's 90, 90% of the team and it's the management team. We have a great management team. Everybody here is very passionate and definitely wanting to be this company, to be successful. So I would say that if it wasn't for the management team, we, we wouldn't be where we're at, honestly.
[00:36:03 - 00:36:19]
Host: Yeah, sure. Well, understanding that you were just thrown in to the deep end and didn't have much prepared and didn't receive like a proper introduction by previous seller. What did the day one speech look like? Or how did you introduce yourselves?
So
[00:36:21 - 00:38:01]
Guest A: we really just introed ourselves saying this is what we're about, this is our values, what we're going to be doing. We're going to be here all the time. And then really we just took questions and one of the first ones is, hey, what's your skin in the game? And that's the answer as I our money, pretty much all of our money.
And then really we just took it from there. I mean, the first few weeks we were. Didn't have a dedicated office. We're up in the conference room.
We're just, just really information gathering, just trying to gather as much information as possible, trying to really get a lay of the land. And we just both kind of dived into everything and we had a whiteboard of, of sticky notes that I actually haven't looked at in a while because we haven't really. We've gotten through pretty much all of it, but it's just said, hey, what's urgent? What's, what's important?
It's Eisenhower's matrix. It's so what's urgent? What's. What's not urgent but not important?
You know, basically just order priority things. You delegate. And it's just really a matter of going bit by bit, handling each thing at a time and really just focusing on each individual thing, not trying to get too sidetracked or unfocused. Um, one of the first areas was the, the pricing and then the marketing and the funnel, the lead flow.
That's one of the first things we tackled then. We obviously, operations, collections, payables, any outstanding customer issues. I mean, really, that's also the other benefit of having a partner. It's, I'm not doing all these tasks myself.
It's, it's, you know, I'm sharing it with another person.
[00:38:02 - 00:38:19]
Host: Yeah, well, given that you, that revenue remained pretty healthy, I guess it was dipping a little bit. But that, this, as you saw it was primarily an expense problem. I would have thought that role task number one would be to look at the PNL and figure out where this money is being leaked out.
[00:38:19 - 00:39:29]
Guest A: So in addition to the pricing. Yes. So in the first two weeks, so one of the big things we did is we, we got a print off of all of our apartments, all of our bills, everything. And we did go line by line and said, okay, what are we using?
If I can't get a justification on what this is in one sentence, you know, we're just getting rid of it. We're cutting it. So in the first two weeks, we cut about a million four worth of annualized expenses. There was just a lot of.
I don't know if it's, I don't know if it. They don't know what they don't know, but they were spending $10,000 a month in cell phones. We didn't need $10,000 a month in cell phones. We got that down to $3,000 a month, which is still maybe a little high.
Sales systems we weren't using, just bleeding expenses that we were just. Weren't utilizing or just straight up just waste. Just wasted money. And we just went line by line and said, hey, what do we need?
What do we don't need? And, you know, I guess I brushed over that. But that's one of the things is we cut a million forward expenses in the first two weeks and annualized, not obviously for that month, but annualized.
[00:39:30 - 00:39:45]
Host: Well, Mike, I mean, like, I, Like I just forewarned the audience that they're going to make. It's. You're making it seem easy. That that was.
That was half your problem. Right. So you're $3 million, losing $3 million a year, and you figure out half of it in your first two weeks.
[00:39:45 - 00:40:21]
Guest A: It's. It sounds so. Yes, but it isn't always so. There's a lot of negotiating.
There's a lot of information gathering. And the month. I mean, in the first few months, I gained 30 pounds and I lost hair. I don't even honestly remember the first two weeks very much because of how little I slept.
Because you're just going. And you almost have to be. You have to be pretty much obsessed about every possible thing and understanding how to prioritize. It's not.
It might sound easy, but it, It's. It isn't easy at all, I can tell you.
[00:40:21 - 00:40:22]
Host: And by the way, I'm. I'm joking.
[00:40:23 - 00:40:25]
Guest A: I know. No, I know, I know, I know.
[00:40:25 - 00:40:33]
Host: For the audience, so they understand, it ain't easy. Was this a sort of. And by the way, you had now moved to Kirkland? Kirkland is a suburb of Seattle.
[00:40:33 - 00:40:39]
Guest A: Yes. It's about 20 minutes away from Seattle. It's. If you go over the bridge.
[00:40:39 - 00:40:53]
Host: Yeah. Great. And so not a part of the country that you are from or. No, you moved there.
And in fact, you told me that you moved there before you had actually signed on the dotted line, so there was also a chance the deal would kick out. But you move there first.
[00:40:54 - 00:41:14]
Guest A: Yep. Well, so we. We flew everything over the night before. We're at a hotel.
And so, yeah, I didn't move all of my things. I still have some things back in Massachusetts, but I pretty much moved all of my stuff over here that I would need. And if it didn't Close. I guess we'd just be flying back.
[00:41:16 - 00:42:47]
Host: Running payroll, paying your bills, closing your books and producing financials. These are critical tasks every business owner must do or oversee. But spending time on them distracts you from the leadership in growth work you want to do. So let system 6 do it for you.
Owned and led by a former Searcher, Chris Williams, System 6 is a leading outsourced finance team for hundreds of SMBs, including over 50 searcher acquired businesses. Chris, Tim and the System 6 team understand firsthand the challenges, the opportunities of jumping into a business as its new owner. So whether you own your business already or have one under LOI, talk to System 6 about how they can give you time back and improve your financial operations. Mention acquiring minds and they'll provide a free review of your books and financial ops, a $500 value.
Check out system6.com, link in the show notes or email helloystem6.com I assume that you, in these first weeks and probably months and maybe still you're just living and breathing the business. I mean you're practically sleeping on the floor. Maybe you literally did that but, but metaphorically you're just the business. You're just everything is the business all day long while you wrap your arms around this crazy.
[00:42:47 - 00:43:19]
Guest A: Yeah, it, it's been a readjustment because I've had to do other things to, to obviously to de. Stress. I, I weightlift a lot, go travel when I can. Still just taking little times of respite to decompress and relax.
I mean that managing that and maintaining that whole other side is really important too. And to, to your answer to your question, there was actually a. Stayed here over the weekend because one of the alarms weren't working and there were a slew of break ins but we ended up not having to do it. So we absolutely would have if we needed to.
[00:43:20 - 00:43:25]
Host: And is your partner working full time in the business at this point in the story?
[00:43:25 - 00:43:28]
Guest A: Yes. Yes, he is. We both are.
[00:43:28 - 00:43:30]
Host: And you, you both have been from day one.
[00:43:31 - 00:43:31]
Guest A: Correct.
[00:43:31 - 00:43:34]
Host: Okay. All right. And so when did you close?
[00:43:35 - 00:43:38]
Guest A: December of 25.
[00:43:39 - 00:44:05]
Host: Okay, so here we are in August. So you're eight months in. And how did people respond to you? Just not in that first day when they're saying, you know, what's skin in game?
But like over the, in the, in the early chapter, not now, but in the early chapters, like who are these guys? Or were they happy to have people come in? What was the, what was the vibe in this, in this faltering H Vac business that's still pretty big.
[00:44:05 - 00:44:55]
Guest A: I would say that it's been, for the most part still pretty positive that it's mostly welcome. A big thing that I think that we both did was not something that we could have done better is get an understanding of everybody's actual skill sets. So, for example, we have a great marketing manager. She's wonderful.
A lot of searchers, I think, look at businesses that are doing between maybe 3, 4, maybe 5 million in revenue, and they're not. They don't have that built out. So I think we, when we took over, we were maybe treating it a little bit too much like a small company. It's not a big company, but it's definitely not a small company.
So I think maybe that's something that we maybe flubbed up on a little bit where we could have done better and that would have created less friction.
[00:44:55 - 00:44:59]
Host: But what do you mean, Mike? You stepped on people's toes and tried to do every.
[00:45:00 - 00:46:10]
Guest A: A little bit. Yeah, a little bit. Not getting a full understanding that, hey, you actually. I actually have a great team and so I'm definitely less involved or less on people's toes now.
But there was an element too of where we're trying to get an understanding of every part of the business. You know, we don't have technical backgrounds. My business partner, he does have a construction background previous before we got into finance. But we have zero H Vac experience.
And so just getting an understanding of the model and learning every possible thing about the business. Business was really a priority and people, people welcomed it because it was some good change. We did have a little bit of turnover when we first bought the business. Some of that was intentional, some of it was not.
But for the most part, we ran one of our first contests and our employee that won it wrote a great email that. Just talking about how our company is a lot different than other H Vac companies in the area. And we've been able to attract a lot of talent. So when we first took over, we had to really go and knock on people's doors to get them to apply.
But now it's trying to come the other way where people are coming to, to want to work here.
[00:46:11 - 00:46:24]
Host: Great. And that's all the culture that you've put in place on that. So on that point, Mike, let's now, let's now go through all the kind of big items that you have done to, to. To turn this around.
And let's start with culture.
[00:46:25 - 00:48:00]
Guest A: I would say the biggest thing is just breaking, breaking through any sort of toxic culture we have A very strong no assholes rule. We've let go of people before. You know, there would be good people, but they weren't a culture fit, toxic. Not being willing to share information, stuff like that, we just don't tolerate.
And so we put that into place and it's taken a lot of buy in from the managers. We put in the EOS entrepreneurial operating system in place. We've implemented that. Not perfectly yet, but we're getting there and just really getting an open dialogue.
Because when we took over, people were operating in silos, saying there was a lot of silo people operating in silos and not sharing information. And I think that's just from what the previous ownership put into place. But now it's hey, everybody's a team, everybody's working together. And it's been really spearheaded by our managers.
Part of that's been building our, our core values, which is essentially we're, we're very merit based. We will take anybody's opinion or we'll take ideas from anywhere and just opening up a dialogue. Some of our best ideas have come from, you know, our frontline employees and just really just listening to them. It's something that I think as somebody with a finance background or search background, people don't value the people diligence enough.
And that was something that we really pressed on in addition, obviously to cutting the expenses and then increasing the top of the funnel. But also the culture is something we've really pressed on.
[00:48:01 - 00:48:09]
Host: You mean since you've been in there, you've tried to change the culture? How much, how much culture diligence had you done before you bought the business?
[00:48:10 - 00:48:25]
Guest A: A little bit. A little bit? Well, it was more of a people diligence than a culture diligence. But coming into it, we knew that morale was pretty low and just, we did everything that we could to get it up and just.
Yeah, and it's, it's, it's gone well so far.
[00:48:25 - 00:49:02]
Host: And so again, that was. Well, kind of structurally or organizationally you implemented eos or you're in the process of implementing eos, you kind of broke down these silos and increased intra department or communication. So so you kind of open things up, you encourage people to voice their ideas. Are, and you, did you explicitly kind of write down and codify these core values or are these just core values that people are picking up by watching, watching you?
[00:49:03 - 00:50:48]
Guest A: No, I have them, them written down. There's six of them. I won't go through all of them. But essentially one of them, for example, is be a Fountain, not a drain.
So that means be willing and honest to open, to share information, to share ideas, to really share your knowledge. So another thing that we do is we're big on trading. It's something that not a lot of companies in the area do at all and actually will steer away from it because they, they think that they have to go, go, go. So in the military, we would take a training day, a half day every month and just focus on our skill sets getting caught up with any certifications.
But it's mostly your technical skills, technical and soft skills. So for example, when we took over the way that install, our install department, our retrofit department did wiring was different than our new construction department. And they would work together sometimes, for example, so we would cause callbacks because they were wiring things differently. So we took one training day, we made a standardized diagram of it, we trained on it, and then all of a sudden we don't have wiring issues anymore.
We had a. Actually, you know, that's an example. On the technical side, we've done brazing everything. On the soft skill side, we had actually a.
An ex FBI hostage negotiator teach our call center people de escalation training. They come in and it's just about constantly improving on the skill sets and developing of the people. And that's another, another key part of our success. So we do weekly short trainings for the team and then we do a monthly training day where we'll take half the day off and, and get caught up on our skills.
[00:50:49 - 00:51:15]
Host: You know, it's, it's. It strikes me as really valuable, but valuable not just in the actual skills that you're training, but that what it signals to the employees about the type of organization that we are. We are an organization that gets better and iterates and is, you know, kind of a. Kind of constant improvement.
Oh yeah, exactly.
[00:51:15 - 00:51:53]
Guest A: Yeah. The Kaizen. Kaizen concept. I'm a big believer in it.
And then it's about going in and having a positive attitude and just realizing that it's a team sport. I mean, that's really it. And I think one of the biggest drivers is when my partner and I are wrong, we admit it. And so I think that was a lack of, hey, if I admit or if I do something wrong, I'll get reprimanded or I'll get in trouble if I take responsibility.
But I think the biggest thing is just taking responsibility. And part of that has just been with my partner and I, when we screw up, we just say, hey, we screwed up. What can we do about it and not trying to move the blame onto somebody else.
[00:51:54 - 00:52:12]
Host: Yeah. You mentioned that you may have stepped on a few toes. That was one of your own missteps to, to keep using the metaphor. Yep.
Were there other missteps that you could share with us now? Things that you think you did wrong in retrospect or. You know, I guess there have been a lot, but maybe a couple of
[00:52:12 - 00:53:11]
Guest A: the biggies, I would say. I mean there's definitely. Well, there's actually one that we talked about today, but there's been a few. I mean we, we make them occasionally.
The one thing I'll say is that's not going to be a perfect timeline or perfect fixing. Any process is never going to be perfect. But I would say we made one bad hire and then it just wasn't a fit. Not a bad person, just wasn't a fit.
And then stepping on toes, definitely not routing and communicating personally information and direction properly. We've really fixed that with the EOS system quite a bit. We still sometimes go off a little bit, but for the most part we're mostly on track and that's really been it primarily. I would definitely say there are things we could have definitely done better.
But you know, on the, on the long run we're, we're going in the right direction. We definitely make mistakes every day though, I can tell you.
[00:53:13 - 00:53:44]
Host: Great. And the going back to numbers now and margin. So you talked about it being around 15, 20%. You've pushed it to 47, 48.
The goal is to push it even higher. That's where healthy H Vac margin territory is. So can you give us more about how you have done that? Was it just the increasing prices or, or, and, and getting out all these, you know, $1.4 million of annual expenses or is there more to say there?
[00:53:45 - 00:55:14]
Guest A: So that, that's a good chunk of it. Just so cost cutting, reclassification, proper classification of expenses, price increases where we've had several, about three to four price increases just across the board doing, getting proper job costing in place. Actually tracking your individual gross profit margin across the board has been really vital and then also to the job mix too. So we were very heavily new construction, much more heavily new construction.
When we took over and we did, we decided to restructure that into. So we have two departments now, service and Install. So we've restructured that department into Install. So we do still some short term remodels, but just getting the job mix to be much more healthy.
So you know, even though we were doing at one point a million five a month. If 700k of it's in new construction work and it's not. And these, these fixed cost, these fixed price contracts that you can't just increase prices on since COVID are, Are killing your margins, it's going to bring your entire, entire blended margin down. And so that was really the, the part of the business that we decided to wind down and just focus on shorter term.
We still do some, but it's just shorter term, but it's just about getting the job mix to more healthy levels. So we're about 85%, 90% service and install or residential service and install now.
[00:55:14 - 00:55:37]
Host: Okay. I want to, I want to press on this a little bit, Mike. So. So new construction is, we all understand, is unappealing from a quality of revenue perspective.
Yes, it's project revenue. It's tied to construction explicitly. Construction is notoriously cyclical. So it's bad for a lot of, a lot of reasons.
Also it sounds like it's bad because it's low margin, which I'm not sure.
[00:55:37 - 00:56:01]
Guest A: I did know you saw a new construction project. If you do a million in revenue, you might do 3 to 5% in net profit. So you might make 50k in that profit. And so it is.
But with the way that the, some of the projects were built bid, it was driving that section, that division's gross profit down in some cases even into the negative.
[00:56:01 - 00:56:02]
Host: Oh, wow.
[00:56:02 - 00:56:04]
Guest A: So it was just bad, bad pricing.
[00:56:04 - 00:56:19]
Host: How much did you see this from the outside, that the business was a heavy, heavily concentrated in new construction, and that's a generally a bad thing. Did you have all of that narrative straight in your head or have you only kind of learned that over these eight, eight months?
[00:56:19 - 00:56:53]
Guest A: We had an idea. We knew and we had the contracts. We had an idea going in that it was something that we'd have to tackle. We could have probably shut it completely down a little bit sooner, but we knew going into it that it would be a tough one and that it was in distress.
I mean, that was really the biggest driver, in my opinion of the company's distress was, was those, those contracts. But we did know. We did. I, I don't think to the degree, but we did know.
[00:56:54 - 00:57:39]
Host: And you know, what I'm struck also by, Mike, is that you've been able to so successfully shift the mix. Because first of all, you've. It sounds like you've shifted it a lot in a relatively short amount of time. And I would have just thought, so you're a residential h.
Vac business. I mean if that's not already clear to the audience, we haven't said that explicitly. So if you're moving away from new construction, what you'd be moving toward is, is service, home service stuff, service calls. And that's notoriously competitive.
I mean H Vac is the industry where there's been a lot of private equity money and consolidation and, and very competitive cost per leads online that go up every year.
[00:57:40 - 00:57:40]
Guest A: So.
[00:57:41 - 00:58:00]
Host: And Kirkland is a mature major metropolitan market. So for all these reasons, I would just think that it would be a very red ocean and very hard to, to, to compete in, especially as guys who are, who are worried about just saving the business, let alone growing the business, of course.
[00:58:00 - 00:58:59]
Guest A: So in, in my opinion, so if you look, for example, Kirkland has about per, per capita twice the amount of H Vac companies as some of the surrounding cities. So we're definitely commoditized. The only way that you can really win in a market like that is through branding and scale. So there are a lot of small 1 and 2 to truck shops that are here.
And it does get annoying because you know, you do have to ebb and flow with the pricing and the supply and demand obviously, but it is absolutely a red ocean. I do think what's going to end up happening in the next year to two years here because of how competitive it is, is we'll have a lot of firms close and there will be, just from what I'm personally seeing, and there will be a little bit less competition. But to your point, you're absolutely right. It would be defined as a red ocean.
[00:59:01 - 00:59:26]
Host: And so in fact, and we heard this from another guest recently, a hyper competitive environment is brutal for the little guys, but actually can be advantageous to the big guys like you because you win in those environments. And sadly for the little guy, they can't survive. They get run out of business and eventually you absorb, absorb their demand.
[00:59:27 - 01:00:17]
Guest A: Yes, yes and no. It depends because. So the little guys, because their fixed costs are lower across the board because usually it's just them doing the back office, they can underbid and discount you. So it's a matter of really knowing your market.
And then it's really all of home services, it's just marketing and logistics. So how well you can fill the top of the funnel and how quickly you can get a technician there and the rest of it is just math and financial engineering. But what I will say is that it has been a little bit rough because there is definitely some commoditization going on. I Don't think that it's.
I don't think that it will be for necessarily ever, but it is rough.
[01:00:17 - 01:00:22]
Host: Well, let me ask you this, Mike. How is specifically demand generation winning new business?
[01:00:23 - 01:02:06]
Guest A: So it's primarily through Google. So you have to have your GVP set up well, you have to have your LSA set up well. You have to understand what are the keywords, what's the drivers. I mean, reviews are really the lifeblood of your business.
Generating reviews, also buying leads, buying marketed leads, leading aggregators, but really just operationally. So the biggest thing that we've been focusing on is being operationally able to stay on top of it. So from obviously call center to the appointment to follow up all across the train. So another part of this is when we took over you is that our call center was broken.
Our call center broken rate was 50% and it was being dragged down. So because we were using a AI system that just, it had no attention to it. It just wasn't set up correctly. And so one of the easiest fixes I will say that we've had is getting on the phone and just saying, hey, this isn't working.
You have a month to fix this or we'll have to go with somebody else. And been working with the firm we were using pretty closely and we're roughly at an 80% booking rate right now. So fixing every part across the chain and operations is really how you, you capture those leads. So in a very roundabout way, what I'm trying to say is the faster and more accurately you can capture those leads and then turn them over and then see the customer, the more likely you are to actually get their business.
So having that level of understanding is really important.
[01:02:07 - 01:02:19]
Host: What did you describe a home services business as? A marketing and logistics business. And so yes, and that's what it is. So elaborate on that.
That's an interesting take.
[01:02:19 - 01:03:39]
Guest A: So it's services pretty much. Whether it's. So we do all three, whether it's plumbing, electrical, H Vac, or if you own a landscaping company or pest control. The fundamentals of it are all the same, is you have to fill the top of the funnel with as many leads as possible, getting the customer in the door, but then also being able to service that customer as quickly as possible.
So if you book out a customer more than three days, what tends to happen is the chances of them going with somebody else or canceling the appointment goes up incrementally, up by up to as much as 80%. So when they call in, or if you use a Marketed lead, they call in, you have to call that customer or pick up the phone within 30 seconds or call them back within a minute. And anything beyond that, your odds of cancellation or losing that lead go up pretty significantly. So essentially getting people in the door, but also being able to service them as quickly as possible.
And on the logistics part too, yes, it's servicing them as quickly as possible, but then also having proper fan stocking, optimizing routes for fuel, you know, making it as low burden rate as possible to wind up a truck and get somebody out there to the customer. So hitting it from both sides, getting them in the door and servicing them as quickly as possible.
[01:03:41 - 01:03:48]
Host: Mike, this knowledge that you have has come in these eight months. You didn't have really this knowledge at all before?
[01:03:50 - 01:04:21]
Guest A: No. So during my search, I did have a little bit of an understanding of this before because I studied industries during my time in finance. Big deep value investor. We did almost buy a restoration company in Virginia that it almost went into underwriting through the sba.
And so I did have some exposure to home services before and I've read a lot of case studies, but a lot of this has just been just kind of diving in and being kind of obsessed with the, the business.
[01:04:22 - 01:04:45]
Host: So eight months in, you've made a lot of progress. Where do you think you are on, you know, percent completed the, the specifically the turnaround. Once you get it 100% turned around, then you're focused on growth. So I don't mean that there's an end to this story, but just the piece of like getting it back to, to our, our term steady state, I
[01:04:45 - 01:06:06]
Guest A: would say 65 or 70%. So it's, the pricing is for the most part fixed. So we have a new. A lot of it is just hey, once a quarter check prices, check material costs, you know, checking those indexes.
If there's any sort of adjustment or if there's any change in fuel costs before actually changing the prices, make sure see what your competitors are doing. So doing a lot of shadow pricing, we've utilized VAs a lot to actually call around the local area and see what other people are charging things like that. Operations, I would say is starting to get there. It's not all the way where we want it to be yet, but it's closer.
I would say overall we're probably when the call center, everything is done, we're probably like 65% of the way. There's because really the biggest thing now is the conversion areas we're focusing on is the conversion and the volume and once those are two are solved, you know, we'll be probably closer to 85%. So I would say, and by my definition of being complete is, you know, we're not really, we're not bleeding money anymore. But what I mean complete is like I want to be doing 100k in net a month, so 7, 5, 100k.
So I, that in my mind that's complete is we're going to be hitting an annualized 1 million in EBITDA.
[01:06:07 - 01:06:24]
Host: Well, quick math. If we're a little bit over or probably 2/3 into the year now, and you're at 65, 70% complete, then by the end of the year, going into 2027, if all goes right, you'll be a million dollar EBITDA to business annualized.
[01:06:24 - 01:06:27]
Guest A: So I mean like for me, just seeing 100k in profit.
[01:06:27 - 01:06:28]
Host: Yes.
[01:06:28 - 01:06:32]
Guest A: We're not doing 100k in profit yet. I, I wish but we'll, we'll be doing it soon.
[01:06:33 - 01:06:38]
Host: But you're, you're targeting January as your first hundred K net month.
[01:06:39 - 01:06:49]
Guest A: Yes. Well, every, I'm always targeting this month as our first 100k month. But yes, I realistically by, by January, I think that's when we'll, we'll hit that first month.
[01:06:49 - 01:07:07]
Host: And so when you get there, when you get there, you and your business partner will be the co equal owners of a $1 million EBITDA business that does 14, $15 million in revenue. You have an investor. How much equity did the two of you retain?
[01:07:08 - 01:07:18]
Guest A: So we both, so we also have some phantom equity to our manager. So we both own about 70% of the business or 65 together. Yes.
[01:07:18 - 01:07:22]
Host: Okay, 65. So each of you call it a third. Basically.
[01:07:22 - 01:07:24]
Guest A: Yeah. Well, if he converts. Yes.
[01:07:25 - 01:07:26]
Host: If your investor converts.
[01:07:26 - 01:07:27]
Guest A: Yep.
[01:07:27 - 01:07:32]
Host: You and your partner will collectively own 6570 or so call it a third each.
[01:07:32 - 01:07:33]
Guest A: Yeah, that's correct.
[01:07:34 - 01:08:01]
Host: Okay, great. Of a business of a million dollar EBITDA H VAC business, white hot market. And that you paid a very low market price for now. You went all in, you pushed all your personal chips in.
So it might not feel like a low price, but again, as you get further and further away from your acquisition and grow the business and the years tick by, it's going to look like you got in for next to nothing.
[01:08:03 - 01:08:21]
Guest A: Pretty much. So with the IRR math that you calculate on the back end doing all the modeling, it's something of 100% IRR per year. So it's some crazy number. If you do the math when I'm able to actually share that number with you.
I actually would be really excited too. I just can't today.
[01:08:24 - 01:08:30]
Host: And by the way, when you're doing that calculation, what are you, what are you looking at as your, as your projected exit?
[01:08:31 - 01:08:49]
Guest A: So we are, we're long term permanent equity. So we don't necessarily have a, we hold minimum 10 years. We're really big into capital allocation. So there's a, if I could plug a book, there's a book called the Compounders.
[01:08:49 - 01:08:49]
Host: Sure.
[01:08:51 - 01:09:08]
Guest A: I don't know if you're familiar with it, but that's the model that we'll be running. And so our goal is to allocate capital into other, other markets. So we're actively looking for sewage, septic, we're looking for restoration. So we want to go into other verticals and invest money into other verticals and build a platform here in the pnw.
[01:09:10 - 01:09:20]
Host: Great. And will this all be Cardinal branded? This, this holding company or home services portfolio or are these new net, New Net. New acquisitions that are apart from Cardinal?
[01:09:21 - 01:10:15]
Guest A: I think it depends circumstantially because if you have a business. So we actually, we decided not to pursue them but we actually made two Lois on other local businesses in the area. One was a few hours away but it had a very strong Google page, stronger than our own Google page and was had a very good marketing presence and so it wouldn't want to change that. So we would keep it.
Some of it would be, you know, XYZ business by Cardinal as a DBA or it would just stay the same name. And then in some cases if there wasn't, I think that marketing set up and if it made sense operationally we could integrate it in there into, into the Cardinal platform. So it's interesting, I don't want to give you a non answer but honestly the honest answer is it completely depends on the situation.
[01:10:16 - 01:11:03]
Host: Yeah, you know, it's interesting. I don't think we talked to it directly really yet, but the people are hearing us mention the brand. So that really appealed to you. You and I both are admirers of great brands.
Cardinal as people are hearing, is the name of the brand bright red. You're in your red shirt, really strong, very kind of consumer friendly brand. Love that. And so that seems like all good.
It is interesting though because if you have a great brand and you kind of think about future acquisitions and those targets have their own brand equity, you, you realize that you can't always just as good a brand as you have in Cardinal slap it on those other brands. So There are limitations to a great brand.
[01:11:04 - 01:11:53]
Guest A: There, there are. I mean, if you have, I'll just use the name widget business that's been around for 50 years that everybody in that local area knows. And then all of a sudden you change it to Cardinal. Yeah, it's a, it's a great brand here.
It has a presence all around Bellevue and Kirkland and definitely in Seattle. But if I go down to Tacoma or if I even go down to Oregon, nobody's going to know who Cardinal is. Sure. But if I'm going and I buy widget business that's been around for 50 years and the Tacoma or down to even Oregon, people are gonna be like, oh, I know that brand.
I love it. Because brand recognition and getting the consumer to subconsciously, I mean, frankly, just think of your brand first. I mean that's really the key. That's why the marketing part is so, so important.
And then obviously the Google GBP and the business page and all of that too.
[01:11:54 - 01:12:14]
Host: Mike, your investor that we mentioned earlier, the equity that they acquired into, into your Cardinal venture here, if you were to buy future businesses, are you raising on a deal by deal basis or does that investors pro rata equity carry through to your entire Holdco that you're going to build for years?
[01:12:15 - 01:13:34]
Guest A: So if we buy anything under the Cardinal umbrella, meaning if we buy it and Cardinal owns the business, then it would be owned. He would, he would have a share in that if he converts. If it's separate from the Holdco, he wouldn't necessarily automatically have ownership in the, in the other acquisitions. But I'd love to, you know, we've had actually a conversation last week and he, you know, if or when, I don't like to say if, when Cardinal is successful, he definitely is interested in investing more and I think he's a great person.
So I would definitely be interested in getting more from. I would definitely take more of his money is what I'm trying to say. And that's one of the biggest things is. So we actually, the other part of this is, even though we were in a distressed situation is we, we did have some suitors that really wanted to invest in us.
And a big part of that is, is making sure you get not just money, but the right type of money. If it's a good deal and it makes sense, you'll raise money. You just want to make sure it's from the right source. But to answer the other part of your question, I would be 100% a proponent of doing the independent sponsor route too.
In the Future that would be, I mean I went to McGuire woods last year. I think it's a, it's a great avenue as well. So I'm, we're, we're open minded is, is what I'm trying to say.
[01:13:35 - 01:14:14]
Host: And Mike, just so following up on your big vision here and how it plays with your current investor, how it plays with your sense of model independent sponsor or not, first, your investor in this deal was comfortable with the idea that you know, if you got this to a particular level of EBITDA or size that you would divert your attention elsewhere while retaining ownership of it. In other words, many, many investors in this asset class want you to show that, want you to show them how you're going to exit and return their, and return their, make give a return on their capital. This investor was fine with you. A long term hold.
[01:14:15 - 01:15:42]
Guest A: Yes. So that was something that we were very, very, very explicit that that was our goal from day one was we want at least a 10 year hold period. Now granted he has a put option so he could force an exit for his shares in year seven. And if it makes sense, I'm, you know, we're happy to exit him but we definitely would want him for the longer term and he feels the same way.
Frankly, he, he is of the same mindset. And as far as attention truly in any, the idea of being an absentee owner and then working four hours a week from your beach in Mexico is not really a realistic outcome for most people. So although we probably won't always be in operations, I'm sitting in the CEO seat right now. We will always allocate capital and work strategically but this business has I think good enough bones operationally to where as we build up more infrastructure we'll be able to be more hands off in it and it will be fine.
And our priority is to find accretive acquisitions for Cardinal. Now we could obviously find something separate but the priority in order of priority it is to find businesses to bolt on to Cardinal. But he is fine with, with what your question is is looking for additional acquisitions and taking the foot off the gas once we're in kind of that steady state. Yes, absolutely.
[01:15:42 - 01:15:50]
Host: Interesting. And then why are you drawn to the independent sponsor model for some future acquisition scale?
[01:15:50 - 01:16:53]
Guest A: I would say that my business partner and I were, we've gotten definitely a lot better at operating. We're decent operators. I would say on our long term vision is that we would definitely want to be more in the capital allocation seat analyzing investments opposed to just operating them and operating. I think you can get a lot more scale.
There is pros and cons to it. Of course. For me personally, I don't necessarily want to care if I'm necessarily the king. I would rather be rich, honestly.
The caveat to that is sometimes I honestly go between wanting to do it and not because of the, the vision, because a lot of those, those providers that do independent sponsor want you to exit in three to five years. So, so I, I do have kind of mixed feelings on it, to be on completely honest with you. But it's something that I would pursue, I, I, I would pursue eventually.
[01:16:54 - 01:16:57]
Host: It sounds like what you want is larger businesses.
[01:16:57 - 01:16:57]
Guest A: Yes.
[01:16:57 - 01:17:02]
Host: Where you're doing capital allocation and, and, and to compound not to have to exit.
[01:17:03 - 01:17:05]
Guest A: Yes, yes, exactly.
[01:17:05 - 01:17:56]
Host: Well, there are capital providers out there, usually in the form of family offices that take a longer term view. And as long as you're extremely upfront with them about wanting to build something over the decades, there are, there are cap, there is capital that's suited to that. It's the minority by far a minority, but you can find it. And certainly as somebody who has been an operator now that is gonna, that is going to reflect very, very well.
It's interesting, Mike, because you've, you've taken, you've bitten off so much here, you and your partner, that I kind of would have thought that you liked operations. But no, this is, this was just a, this was a means to an end get you kind of getting into business is your first time and this is how you did it. But it's not, it's not what you foresee being. You know, you're not a turnaround guy.
That's not what you're here to do. So
[01:17:58 - 01:18:59]
Guest A: long term. No long term, I would love to be able to invest and to purchase and to back people just because I believe that you can go much further with a group of people than just yourself. So as far as priority, I just see ourselves being more in capital allocators. And when I mean long term, I mean like 15, 20 years from now, 10, 15, 20 years.
In the short term, if there was another business that made sense, bring on the brain damage. I would love to be the turnaround guy and buy a distressed business. I would say that we're decent at it, we're decent at operations. I would just say our bigger strength though in the long term is capital allocation.
So that's the reason why I'm saying that. But I don't necessarily mind being the CEO. It's, it's just not where I think our strength is long term, but we find a few deep value opportunities or something distressed. That makes sense.
I mean, heck, yeah, I'd be all for it.
[01:19:01 - 01:19:39]
Host: Last question for you, Mike. Circling back to your skin in game. Your. The risk here, by the way, we.
We haven't explicitly said that because you didn't take an SBA loan, there's no personal guarantee. So while you did basically clear out your bank account to do this, you're not going to. The risk of bankruptcy and how that would tarnish your. Your credit, for example, is not there.
You're not going to lose a home. I don't mean to. I don't mean to. You know, I don't mean to minimize the risk here, but do you not feel like that's a pretty big distinction?
[01:19:40 - 01:20:10]
Guest A: It is. So the caveat to that is that some of our vendors, we may have to take personal guarantees in the future. With some of our vendors, we push very heavily against it. So there is that possibility.
But as far as an SBA loan, no, no, there's. There's no SBA loan. So to your point, yes, there it would be. If it went to zero, it wouldn't necessarily have a personal guarantee to worry about.
[01:20:11 - 01:20:32]
Host: So now that you're eight months in, things are going well. Despite the brain damage, how do you reflect now on the risk that you took or how heavily does the risk of this turnaround weigh on you? Do you feel like, have you gotten a lot of confidence or do you still have fetal position moments? What's it like inside your head these days?
[01:20:32 - 01:21:18]
Guest A: It's a bit bipolar. It depends on the hour. But what I'll say is that it's mostly confident. Like, I know that we will be successful and turn the business around.
What I will say is the things that we could have done better is when we make a bad decision, pivot on it faster, identify it more, come up within a plan, take action on it faster, or if make it have bad higher, fire faster. But overall, working to just be proactive and not reactionary, if that makes sense. But overall, I have a lot of confidence. It does ebb and flow a little bit, honestly still.
But a lot of it is. It's helped by having a great, you know, an awesome business partner and a great team. So without. Without them, you know, wouldn't be able to do it.
But it's really. It just really comes down to that.
[01:21:18 - 01:21:21]
Host: Great. Mike, anything that you wanted to say that we didn't get to, I would
[01:21:21 - 01:21:35]
Guest A: just say the biggest thing is regardless, because this is obviously a layer of extra difficulty. But you know, regular acquisitions aren't easy themselves. It's big thing to, to still take care of yourself and take care of your health while you are doing it. It's, it's underrated.
[01:21:35 - 01:21:39]
Host: Did you get those 20 or 30 pounds back off or you just converted them to muscle?
[01:21:39 - 01:21:51]
Guest A: No, I'm trying to slowly so I, I've had a few little, little, little nagging injuries, but I'm slowly, slowly getting there and I need to lose about maybe at this point, maybe a hundred pounds, but I'm getting there.
[01:21:52 - 01:22:10]
Host: Okay. All right, Mike. Well, great stuff. Thanks for coming on.
Thanks for sharing. This is such an unusual story and a hopeful one. You guys seem to be clearly on the right track. So we're rooting for you and we'll link to you in the show notes.
Link to your LinkedIn in the show notes. And again, thanks for coming on Acquiring Minds.
[01:22:10 - 01:22:13]
Guest A: Mike Bourgeois Thanks, Will. Thanks for having me.
[01:22:13 - 01:23:00]
Host: Hope you enjoyed that interview. Don't forget to subscribe to the Acquiring Minds newsletter. We send an email for every episode with an introduction to the interview, a link to the the video version on YouTube, and soon, key takeaways, numbers and more essentials from the interview. For those of you who don't have time to listen or watch it, subscribe at acquiringminds Co.
You'll also find all our webinars there on the website, both those we have coming up and recordings of past webinars. At this point, There are over 30 webinar recordings, a wealth of information on all the technical nitty gritty of buying a business. Acquiringminds copy.